
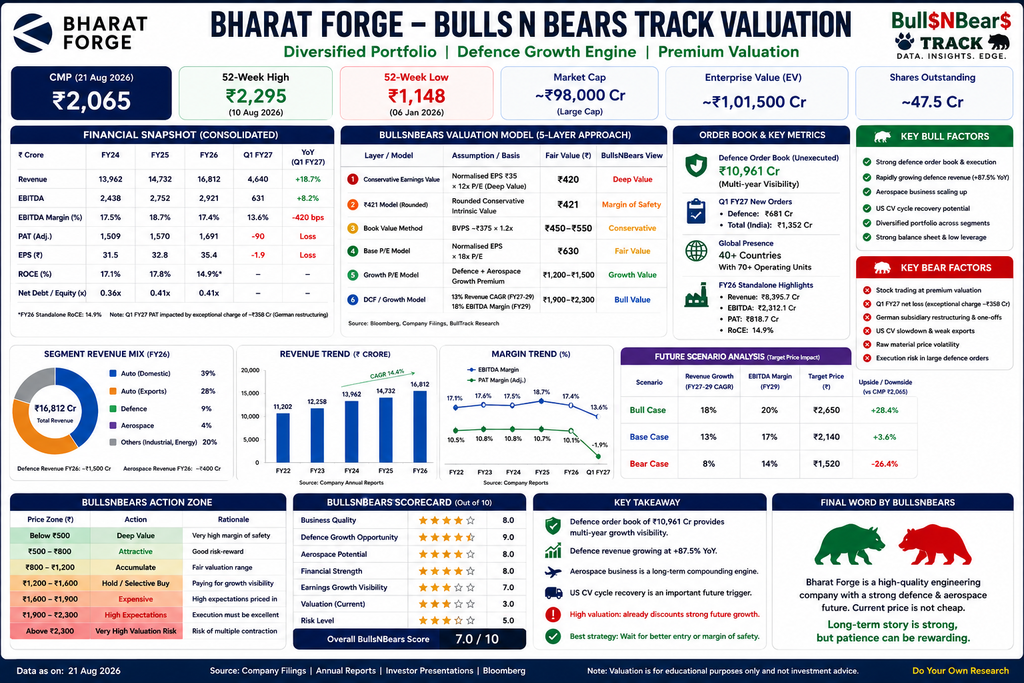
Bharat Forge Share Price: A Strong Defence Story, But Valuation Is the Key Risk
5
Bharat Forge Ltd. has gradually transformed from a traditional auto-component and forging company into a diversified engineering business with significant exposure to defence, aerospace, industrial components and commercial vehicles.
The investment story has become particularly interesting because the company’s defence business is expanding rapidly at a time when the traditional automotive business is facing cyclical pressure.
However, there is another side to the story: the stock is already trading at a premium valuation, meaning investors are paying today for a significant portion of the expected FY27–FY28 growth.
That makes Bharat Forge an interesting long-term defence + aerospace story, but not necessarily a low-risk stock at current valuations.
Bharat Forge: Latest Numbers Investors Should Know
The latest Q1 FY27 results provide a much more updated picture than the FY26 numbers shown in the original presentation.
| Metric | Q1 FY27 | YoY |
|---|---|---|
| Consolidated Revenue | ₹4,639.94 Cr | +18.7% |
| Total Income | ~₹4,697 Cr | +18.7% |
| Defence Revenue | ₹495.68 Cr | +87.5% |
| Forgings Revenue | ₹3,831 Cr | +7.7% |
| Others Revenue | ₹627.86 Cr | +125% |
| Net Profit | -₹89.7 Cr | Sharp decline |
| Exceptional Charge | ~₹358 Cr | Major impact |
| Defence New Orders | ₹681 Cr | Q1 FY27 |
| Indian New Orders | ₹1,352 Cr | Q1 FY27 |
| Defence Order Book | ~₹11,196 Cr | Multi-year visibility |
The most important point is that revenue growth remained strong even though reported profit collapsed.
1. Revenue Growth Is Still Strong
Bharat Forge reported consolidated revenue of approximately ₹4,640 crore in Q1 FY27, compared with ₹3,909 crore in Q1 FY26.
That represents roughly 18.7% YoY growth.
This is important because the company is growing despite weakness in parts of the global commercial-vehicle market.
The growth is increasingly coming from businesses outside the traditional auto segment.
Why this matters
The old Bharat Forge investment thesis was heavily dependent on:
- Auto components
- Commercial vehicles
- Global forging demand
- North American truck cycle
The new thesis is broader:
Auto + Defence + Aerospace + Industrial + New Energy/EV opportunities
That diversification could reduce the company’s dependence on any single industry cycle.
2. Defence Is Becoming the Biggest Growth Catalyst
This is arguably the most important part of the Bharat Forge story.
Defence revenue increased approximately 87.5% YoY to ₹495.68 crore in Q1 FY27.
Even more interesting is the company’s defence order pipeline.
The Q1 FY27 investor presentation indicated ₹681 crore of new defence orders during the quarter, while the defence order book was around ₹11,196 crore.
This gives the business multi-year revenue visibility.
Major defence opportunities
Bharat Forge’s defence portfolio includes areas such as:
- Artillery systems
- Ammunition
- Armoured platforms
- Small arms
- Defence vehicles
- Weapon systems
- Engineering and systems integration
The company has also been expanding its capabilities rather than remaining only a component supplier.
3. The ₹11,000+ Crore Defence Order Book Is the Real Story
One number investors should watch closely is:
Defence Order Book: ~₹11,196 Crore
This is considerably larger than the current quarterly defence revenue.
That creates a potential multi-year revenue visibility.
But investors should remember:
Order book ≠ immediate revenue ≠ immediate profit.
The key question is how quickly Bharat Forge can convert these orders into actual production, revenue and EBITDA.
Therefore, upcoming quarters should be judged on execution, not merely on new order announcements.
4. Aerospace Could Become the Silent Compounder
The second major pillar is aerospace.
The company reported aerospace revenue of around ₹400 crore in FY26, with approximately 20% YoY growth according to the presentation data shown in your screenshots.
This business is attractive because aerospace programmes generally have:
- Long product cycles
- High qualification barriers
- Higher entry barriers
- Long customer relationships
- Potentially attractive margins
Bharat Forge’s aerospace exposure therefore provides another diversification layer beyond defence.
The company’s aerospace subsidiary and international capabilities could become increasingly important over the next several years.
5. The US Commercial Vehicle Cycle Is Still a Problem
Not everything is bullish.
Bharat Forge’s traditional automotive business remains exposed to the global commercial-vehicle cycle.
The US Class 8 truck market has historically been an important export market for the company.
When truck production slows, component demand and export revenue can come under pressure.
The company has previously highlighted weakness in the North American commercial-vehicle market and regulatory/demand challenges.
The positive argument is that if the US CV cycle recovers, Bharat Forge could benefit from operating leverage.
In simple terms:
Low volumes → pressure on margins
Higher volumes → fixed-cost absorption → potential margin improvement
This is why the recovery of the US commercial-vehicle cycle remains an important FY27–FY28 trigger.
6. Q1 FY27 Profit Was the Biggest Red Flag
This is where investors need to be careful.
Despite revenue growth of nearly 19%, Bharat Forge reported a consolidated net loss of about ₹89.7 crore, compared with a profit of about ₹283.7 crore in Q1 FY26.
The major reason was an exceptional charge of roughly ₹358 crore.
A significant portion was related to restructuring and provisions associated with the German subsidiary Bharat Forge CDP GmbH.
So the headline loss does not necessarily mean that the core Indian business suddenly became structurally unprofitable.
But it does highlight a real risk:
Global subsidiaries can continue to create volatility.
7. German Subsidiary: The Problem Investors Cannot Ignore
The German business has been under pressure from:
- Market challenges
- Cost disadvantages
- Restructuring requirements
- Labour-related costs
- Weak operating conditions
Bharat Forge has initiated restructuring measures for the German subsidiary.
The positive scenario is that restructuring eventually reduces losses.
The negative scenario is that investors continue to see:
Exceptional charges → weaker consolidated earnings → lower valuation confidence.
Therefore, the German business should remain on the watchlist for every quarterly result.
8. FY26 Was Still a Strong Base
Before judging the company purely on Q1 FY27, it is worth looking at FY26.
Bharat Forge ended FY26 with approximately:
- Revenue: ₹16,812 crore
- EBITDA: ₹2,921 crore
- Revenue growth: ~11%
- EBITDA growth: ~6%
The company also secured approximately ₹4,814 crore of new business during FY26, including around ₹2,816 crore from Defence.
That shows the defence transition was already visible before FY27.
9. Balance Sheet Is a Positive
One of the stronger aspects of Bharat Forge is its balance sheet.
At FY26-end, consolidated net debt-to-equity was around 0.41x, according to the company’s Q4 FY26 conference call.
The Q4 FY26 presentation also highlighted a strong balance-sheet position.
A relatively manageable debt burden gives the company more flexibility to invest in:
- Defence
- Aerospace
- Manufacturing capacity
- Technology
- New businesses
However, investors should monitor the proposed fundraising.
10. ₹2,500 Crore Fundraising: Why It Matters
In August 2026, the board approved a proposal to raise ₹2,500 crore, subject to shareholder approval.
Fundraising itself is not necessarily negative.
The important question is:
Where will the money be deployed?
If capital goes toward high-return growth opportunities such as:
Defence + Aerospace + Advanced Manufacturing
it could potentially strengthen long-term earnings.
But if capital is repeatedly required to support weaker businesses, investors should become more cautious.
11. Bharat Forge Share Price & Valuation
This is where the investment story becomes complicated.
The stock touched a 52-week/all-time high around ₹2,295 on 10 August 2026.
By 21 August 2026, it was around ₹2,065, meaning the stock had already corrected substantially from that high.
The market capitalisation was around ₹98,000+ crore in the latest available data.
This tells us something important:
The market is already assigning a significant premium to Bharat Forge’s future defence and aerospace earnings.
Therefore, the stock needs strong execution to justify that premium.
12. Brokerage Targets Show a Wide Range
Your screenshots show a very wide difference in brokerage views:
| Brokerage | View | Target |
|---|---|---|
| Jefferies | Buy | ₹2,500 |
| Morgan Stanley | Overweight | ₹1,978 |
| Motilal Oswal | Neutral | ₹1,835 |
| Kotak | Sell | ₹1,300 |
| Citi | Sell | ₹1,060 |
The wide target-price range itself is a warning.
It tells investors that Bharat Forge’s valuation depends heavily on assumptions about future defence and aerospace earnings.
In other words:
The debate isn’t whether Bharat Forge has a good business.
The debate is:
How much should investors pay for that future growth?
13. Three-Pillar Bull Thesis
I would divide the long-term Bharat Forge bull case into three major pillars.
🛡️ Pillar 1 — Defence
Order book ~₹11,196 crore
Potential multi-year growth visibility.
✈️ Pillar 2 — Aerospace
Approximately ₹400 crore FY26 revenue and growing.
Potentially attractive long-term business characteristics.
🚛 Pillar 3 — US Commercial Vehicles
If the US CV cycle bottoms and recovers, Bharat Forge’s traditional business could benefit through operating leverage.
Together:
Defence + Aerospace + CV recovery = potential FY27–FY28 earnings acceleration.
14. What Can Go Wrong?
Investors should not ignore the risks.
🔴 Risk 1: Valuation
The stock is already trading at a premium valuation.
🔴 Risk 2: Margin Pressure
Revenue growth has not automatically translated into equivalent profit growth.
🔴 Risk 3: German Business
Restructuring may generate additional costs.
🔴 Risk 4: US CV Weakness
A prolonged commercial-vehicle slowdown could hurt exports.
🔴 Risk 5: Defence Execution
Large order books are attractive, but execution delays can postpone revenue recognition.
🔴 Risk 6: Fundraising/Dilution
A ₹2,500 crore fundraise could affect capital structure depending on the final route.
Bharat Forge Bull vs Bear Case
| Bull Case 🟢 | Bear Case 🔴 |
|---|---|
| Defence order book >₹11,000 Cr | Valuation already expensive |
| Defence revenue +87.5% YoY | Q1 FY27 net loss |
| Aerospace growing | Margin compression |
| US CV recovery | Weak global auto demand |
| Strong Indian manufacturing growth outlook | German restructuring |
| Multi-year defence visibility | Execution risk |
| Diversified business | Potential capital dilution |
What Should Investors Watch Next?
For the next 4–6 quarters, I would track these 7 numbers rather than simply watching the share price:
1. Defence Revenue
Can it sustain >20–30% growth?
2. Defence Order Execution
How quickly is the ₹11,196 crore order book converting into revenue?
3. EBITDA Margin
Can margins recover toward the FY26 standalone level?
4. German Losses
Are restructuring costs declining?
5. US CV Volumes
Is the North American truck cycle actually recovering?
6. Aerospace Growth
Can aerospace become a ₹500–₹1,000+ crore business over time?
7. ROCE / ROE
Does earnings growth justify the premium valuation?
My BullTrack View
Long-Term: 🟢 Positive
Near-Term: 🟡 Cautious
Valuation: 🔴 Expensive
Defence Story: 🟢 Strong
Execution: 🟡 Must Watch
The most interesting part of Bharat Forge is no longer simply its traditional forging business.
The company is attempting to create a higher-value engineering platform around Defence + Aerospace + Advanced Manufacturing, while retaining its automotive base.
That transition can potentially create significant shareholder value over the next 2–3 years.
But at a share price above ₹2,000, investors are not buying the stock purely for today’s earnings.
They are effectively paying for future earnings growth.
Therefore, chasing the stock after sharp rallies can be risky.
Final Verdict
Bharat Forge is a high-quality long-term transformation story, but it is not a cheap stock.
The strongest part of the thesis is the ₹11,000+ crore defence order book, rapidly growing defence revenue, aerospace expansion and potential recovery in the US commercial-vehicle cycle.
The biggest concerns are valuation, margin pressure, German restructuring and the ability to convert the defence order book into profitable revenue.
My overall view:
Business Quality: ⭐⭐⭐⭐☆
Defence Opportunity: ⭐⭐⭐⭐⭐
Aerospace Opportunity: ⭐⭐⭐⭐☆
Balance Sheet: ⭐⭐⭐⭐☆
Growth Potential: ⭐⭐⭐⭐⭐
Current Valuation: ⭐⭐☆☆☆
Risk/Reward at ₹2,000+: ⭐⭐⭐☆☆
🐂 BullsNBears Action Zone
| Share Price | Action |
|---|---|
| Below ₹500 | 🟢 Deep Value |
| ₹500–₹800 | 🟢 Attractive |
| ₹800–₹1,200 | 🟢 Accumulate |
| ₹1,200–₹1,600 | 🟡 Hold / Selective Buy |
| ₹1,600–₹1,900 | 🟠 Expensive |
| ₹1,900–₹2,300 | 🔴 High Expectations |
| Above ₹2,300 | 🔴 Very High Valuation Risk |
For a 2–3 year investor, the defence and aerospace story remains attractive. For a short-term trader, however, the stock’s proximity to its 52-week high and elevated valuation make risk management much more important.
The next major confirmation should come from defence order execution, margin recovery and Q2/Q3 FY27 earnings, rather than another headline order announcement.
Disclaimer
This article is for educational and informational purposes only and should not be considered investment advice, a recommendation to buy or sell Bharat Forge shares, or a guarantee of future returns. Stock prices can be highly volatile. Investors should conduct their own research and consider their risk tolerance, valuation, financial position, and investment horizon before making any investment decision. Past performance and order-book growth do not guarantee future returns.