
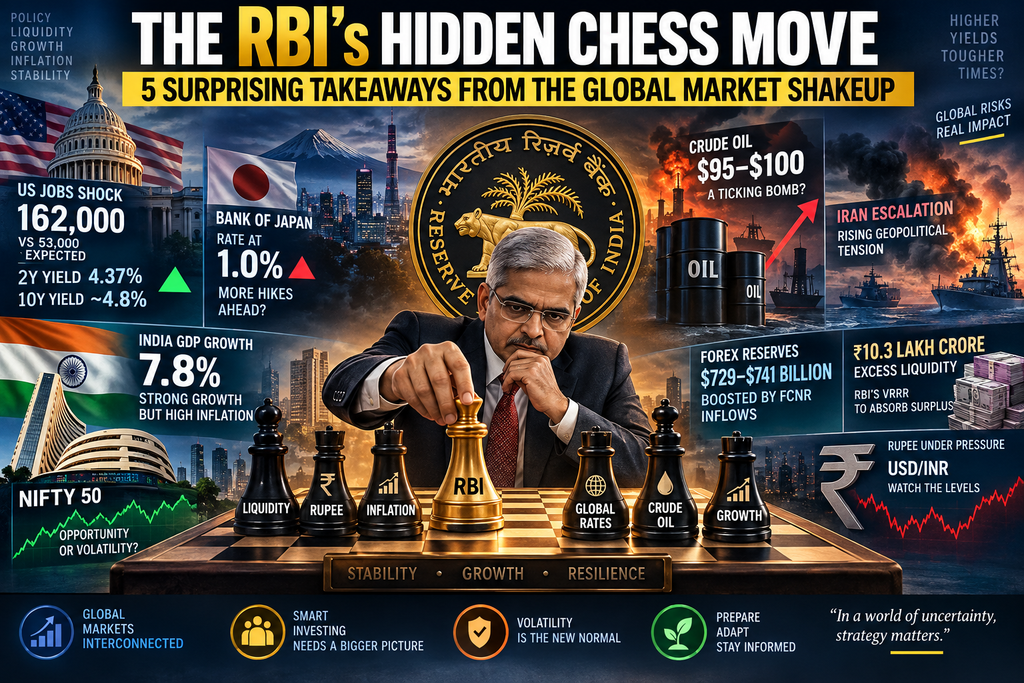
The Indian stock market is facing an unusual macroeconomic puzzle.
India’s economy is growing rapidly—but the global cost of money is rising at exactly the wrong time.
The US 10-Year Treasury yield has moved close to 5%, Brent crude has pushed toward $100 a barrel, the Japanese yen has strengthened sharply, and expectations of further global monetary tightening are returning. Reuters reports that the US 10-year yield has approached a level not sustainably seen in roughly two decades, creating pressure on equity valuations and corporate borrowing costs.
At the same time, India has received an extraordinary wave of foreign-currency inflows.
The result?
The Reserve Bank of India is suddenly dealing with a problem that sounds almost contradictory:
India has too much liquidity at precisely the moment when global financial conditions are becoming tighter.
That is where the RBI’s latest moves become important.
The central bank is not simply defending the rupee.
It is trying to manage liquidity, inflation, foreign capital, crude oil and monetary transmission simultaneously.
And the numbers reveal just how unusual this situation has become.
1. The US Jobs Shock Has Rewritten the Rate-Cut Story
The first shock came from the United States.
August US nonfarm payrolls increased by 162,000, dramatically above the roughly 56,000 consensus forecast reported around the release. The unemployment rate remained at 4.1%.
That immediately changed the interest-rate equation.
The stronger labor market reduced the urgency for the Federal Reserve to cut rates and pushed Treasury yields higher.
The 2-year Treasury yield briefly reached approximately 4.37%, its highest level since January 2025, while the 10-year yield moved toward 4.8%.
The latest market pricing is even more interesting.
Reuters reported on September 8 that the market was assigning roughly a 60.6% probability of a Fed rate increase at the upcoming meeting.
The Federal Reserve’s most recent official decision kept the federal-funds target range at 3.50%-3.75%, while three FOMC members wanted a 25-basis-point increase at that meeting.
Why this matters for India
If US rates remain higher for longer:
US yields ↑ → Dollar pressure ↑ → FII risk appetite ↓ → Rupee pressure ↑ → RBI flexibility ↓
That is the first part of the chessboard.
2. India Is Growing at 7.8%—But Inflation and Oil Are Complicating the Victory
India’s latest GDP number looks spectacular.
Real GDP expanded by 7.8% in the April-June quarter of 2026, surprising economists and prompting several institutions to raise their FY27 growth expectations.
But the inflation picture is less comfortable.
India’s July retail inflation was around 4.45%, above the RBI’s 4% medium-term target. Economists have also warned that crude oil and geopolitical risks could push inflation higher.
And this is where the RBI faces a difficult trade-off.
Its policy repo rate is currently:
5.25%
The RBI’s official data also shows:
- SDF: 5.00%
- MSF: 5.50%
- CRR: 3.00%
- SLR: 18.00%
A Reuters poll in July showed economists expected the RBI to keep the repo rate at 5.25% through the remainder of 2026, reflecting concerns that aggressive tightening could hurt growth.
So the RBI is essentially balancing:
Growth vs Inflation
Currency stability vs Monetary easing
Domestic liquidity vs External financial conditions
This is why the RBI’s next moves may be much more about liquidity management than simply changing the repo rate.
3. The $729 Billion Reserve Story Is More Complicated Than It Looks
India’s foreign-exchange reserves have reached historic levels.
Recent RBI data showed reserves at approximately $740.8 billion for the week ending August 28, following a huge increase linked to foreign-currency inflows.
That is an enormous war chest.
But here’s the important distinction:
Not all of this represents permanent capital.
The RBI’s special foreign-currency deposit scheme attracted approximately $127.23 billion, according to Reuters, creating an estimated ₹9.70 lakh crore liquidity surplus in the banking system.
A broader set of special measures generated approximately $136.4 billion of inflows, helping push reserves to record levels.
So the headline:
“India has $729-$741 billion of reserves.”
is only half the story.
The other half is:
“What liabilities and future hedging obligations came with those inflows?”
Reuters reports that the RBI’s forward-dollar liabilities have reached approximately $137 billion.
This doesn’t mean India’s reserves are fake.
Far from it.
It means investors need to distinguish between:
Reserve assets
and
the liabilities created while attracting foreign currency.
That is the hidden part of the chessboard.
4. The RBI’s ₹10.3 Lakh Crore Liquidity Problem
This is perhaps the most important development for Indian banks.
Foreign-currency inflows were converted into rupees through the banking system.
That created an enormous liquidity surplus.
By September 3, the banking system’s liquidity surplus had reached approximately:
₹10.3 lakh crore
Reuters reports that the RBI responded with a 30-day VRRR auction worth ₹7 lakh crore, designed specifically to absorb some of this excess liquidity.
Think of VRRR as a giant financial sponge.
The RBI effectively tells banks:
“You have too much cash. Park some of it with us.”
The money remains within the financial system, but it is temporarily removed from active circulation.
Why is this important?
Because excessive liquidity can push short-term market rates below the RBI’s desired operating zone.
And when market rates become disconnected from the policy rate, monetary-policy transmission becomes less effective.
The RBI therefore has two different jobs:
Job 1: Keep enough liquidity available to support growth.
Job 2: Prevent so much liquidity from flooding the system that inflation and asset-price distortions accelerate.
That is the balancing act.
5. The Call Rate vs Repo Rate Is a Critical Signal
The RBI’s repo rate is 5.25%.
But money-market rates can trade below that level when liquidity becomes excessive.
The RBI’s official market data has shown call rates trading within a broad range below and around the policy rate during recent periods.
This is why investors should not look at the repo rate alone.
A better dashboard is:
Repo Rate
What the RBI officially wants.
Call Rate
What banks are actually paying for overnight liquidity.
VRRR Absorption
How aggressively the RBI is removing excess liquidity.
CRR
How much liquidity banks must hold with the RBI.
Together, these tell you much more about the actual stance of monetary policy.
6. The Bank of Japan Is Now a Bigger Risk Than Before
The original narrative that the BOJ was merely preparing for a move toward 0.5% is now outdated.
The Bank of Japan currently guides the uncollateralized overnight call rate at approximately:
1.0%
The BOJ raised the rate to this level in June 2026 and maintained it at its July 31 meeting.
And another important meeting is scheduled for:
September 17-18, 2026
Markets are now watching for the possibility of another 25-basis-point hike, although that remains a market expectation rather than a confirmed decision. Reuters reported that expectations for a September hike have contributed to a sharp yen rally.
Why should an Indian investor care?
Because Japan has historically been one of the world’s most important sources of cheap funding.
If Japanese interest rates rise:
Yen ↑
Carry trades become less attractive
Global leveraged positions can unwind
Risk assets can become more volatile
That can hit emerging markets—including India.
7. The Crude Oil Bomb Is Moving Toward $100
This is perhaps the biggest near-term risk for India.
Brent crude has moved sharply higher as the US-Iran conflict intensifies and attacks disrupt energy infrastructure.
On September 8, Brent approached $100 per barrel, with Reuters reporting a high around $99.46 following attacks on Saudi energy facilities.
Another Reuters report put Brent around $98.66 in Tuesday trading.
For India, crude is critical because India imports a substantial portion of its oil requirements.
Higher crude can therefore create a chain reaction:
Oil ↑
↓
India’s import bill ↑
↓
Current-account pressure ↑
↓
Rupee pressure ↑
↓
Imported inflation ↑
↓
RBI rate-cut flexibility ↓
This is why the $100 crude level is psychologically important.
8. The Iran-US Conflict Is No Longer a Background Risk
The geopolitical situation has also moved beyond simple rhetoric.
Reuters reported that US forces struck three Iranian crude-oil tankers after ballistic missiles were launched toward two US Navy ships.
Iran has also threatened further restrictions around the Strait of Hormuz.
The Strait is one of the world’s most important oil shipping routes, making any sustained disruption potentially significant for global energy prices.
This changes the market equation.
Previously, investors could treat geopolitical risk as a headline.
Now the market must consider:
How much physical oil can actually reach global consumers?
That is a much more important question.
9. What Happens to Nifty If Oil Breaks $100?
There are three possible scenarios.
Scenario A: Brent remains below $100
The RBI gets some breathing room.
The rupee remains manageable.
Indian equities can absorb the global volatility.
Scenario B: Brent sustains above $100
Pressure increases on:
- rupee
- inflation
- current account
- bond yields
- RBI policy flexibility
Nifty valuations could become more vulnerable.
Scenario C: Brent moves toward $110-$120
That becomes a much more serious macro shock.
The combination of:
Oil ↑ + US yields ↑ + Dollar ↑
would be particularly uncomfortable for emerging markets.
10. FII Positioning Is Bearish—but Not a One-Way Bet
There is another important divergence in Indian markets.
Foreign investors have been cautious, but the derivatives data does not support a simplistic “FIIs are only short” narrative.
CDSL data shows significant FII index-futures open interest and active buying and selling across derivatives.
And recent cash-market data shows that September has actually seen positive FII flows so far, while domestic institutions have been much stronger buyers.
Through September 7:
FII net buying: approximately ₹2,654 crore
DII net buying: approximately ₹19,134 crore
This is extremely important.
It means India’s market structure has changed.
Foreign investors can create volatility.
But domestic institutions can increasingly provide a floor.
11. The DII Shield Is Becoming India’s Secret Weapon
This is one of the biggest structural differences between today’s Indian market and previous cycles.
India now has a massive domestic savings engine.
Money flows through:
- SIPs
- mutual funds
- insurance
- NPS
- retirement savings
- direct equity participation
Therefore, when foreign investors sell, domestic investors don’t necessarily sit on the sidelines.
They can absorb a significant portion of the supply.
This doesn’t make Nifty immune.
But it can reduce the probability of a disorderly collapse.
12. The RBI’s Real Chessboard
Put all the pieces together.
The RBI is currently facing at least five simultaneous pressures:
1. US Treasury yields
Higher global discount rates.
2. Crude oil
Higher imported inflation risk.
3. Rupee
Currency stability challenge.
4. Excess liquidity
₹10.3 lakh crore banking-system surplus.
5. Growth
7.8% GDP growth argues against unnecessarily aggressive tightening.
This explains why the RBI is using multiple tools instead of relying solely on the repo rate.
The toolbox includes:
VRRR
CRR
FX intervention
Dollar-rupee swaps
OMO operations
Market Stabilisation Scheme
Reuters reports that these are among the possible or active tools being considered to manage the liquidity surge.
13. The Biggest Surprise: RBI Can Be Tight Without Hiking Rates
This is perhaps the most important takeaway.
Many retail investors assume:
RBI tightening = repo rate hike.
Not necessarily.
The RBI can tighten effective financial conditions through liquidity management.
For example:
Repo = 5.25%
But if the RBI aggressively absorbs excess liquidity through VRRR, CRR, or other operations, the effective monetary environment can become tighter without changing the headline repo rate.
This is the RBI’s hidden chess move.
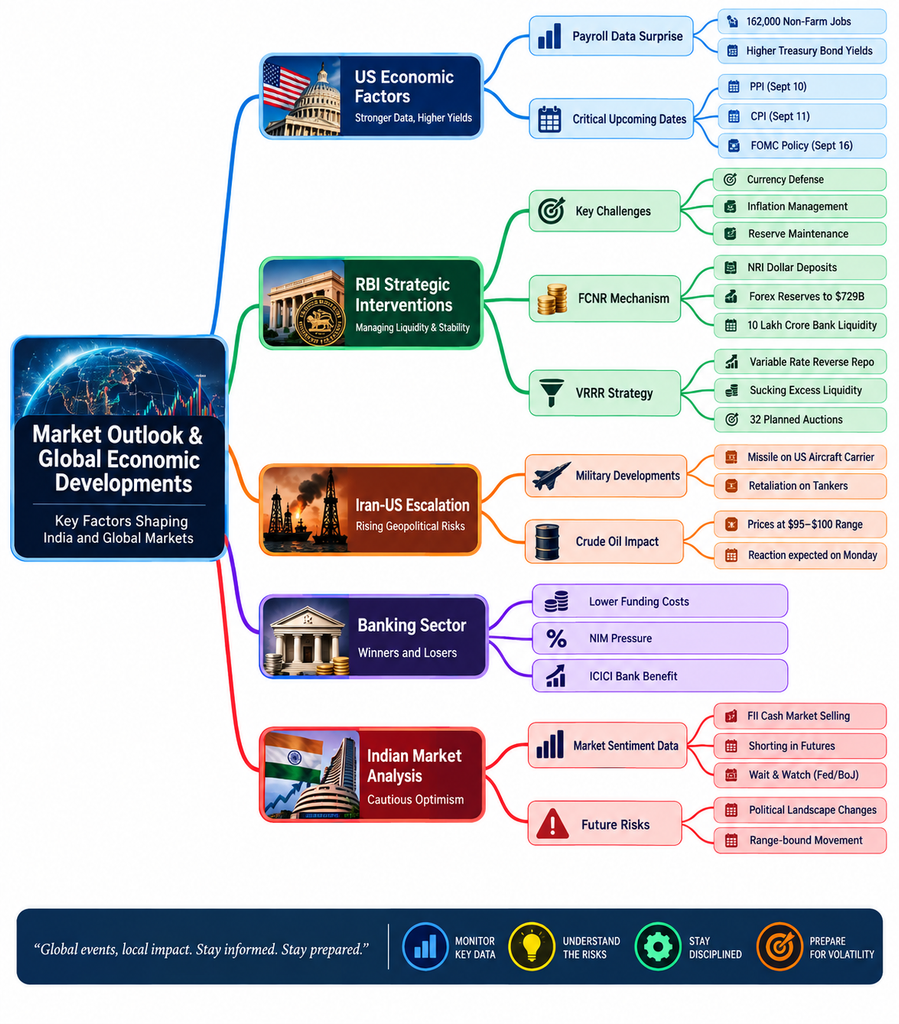
14. The Next Big Trigger: US PPI and CPI
Investors now have two extremely important US inflation releases.
September 10
US PPI for August
September 11
US CPI for August
The Bureau of Labor Statistics confirms both release dates at 8:30 a.m. ET.
These numbers matter because the Fed’s September meeting is scheduled for September 15-16.
So the sequence is:
Jobs data → PPI → CPI → Fed decision
If inflation remains sticky, rate-hike expectations could strengthen.
If inflation cools sharply, Treasury yields could retreat.
And that would potentially provide relief to:
- Nifty
- Nasdaq
- Bitcoin
- emerging markets
- Indian bonds
- the rupee
15. Three Market Scenarios Investors Should Watch
🟢 Bullish Scenario
US CPI cools + oil falls + Treasury yields decline + BOJ stays cautious
Potential result:
- Nifty relief rally
- rupee stabilizes
- FII selling slows
- technology stocks recover
- Bitcoin benefits from easier liquidity expectations
🟡 Neutral Scenario
Oil remains around $95-$100 + US inflation stays sticky + RBI absorbs liquidity
Potential result:
- Nifty remains range-bound
- volatility stays elevated
- domestic investors support declines
- FIIs remain selective
This may be the most likely short-term environment if neither side of the macro equation breaks decisively.
🔴 Bearish Scenario
Oil >$100 + US CPI hot + Treasury yield >5% + BOJ hikes
That would create a powerful global tightening combination:
Oil ↑
Inflation ↑
US yields ↑
Yen ↑
Carry trades ↓
Dollar volatility ↑
FII risk appetite ↓
For Indian equities, this would be the most dangerous configuration.
16. The Five Numbers I Would Watch Every Morning
Instead of looking at hundreds of headlines, investors can track five numbers.
1. US 10-Year Treasury Yield
Key zone: 5%
2. Brent Crude
Key zone: $100
3. USD/INR
Measures currency stress.
4. India Call Rate vs Repo
Measures liquidity transmission.
5. Nifty 50
The final market response.
And add two event indicators:
US CPI/PPI
BOJ policy decision
That gives you a much clearer macro dashboard.
Conclusion: The RBI Is Not Fighting One Battle
The biggest mistake would be to interpret the current market purely through the lens of interest rates.
This is much bigger.
India is experiencing a rare combination of:
7.8% GDP growth
record FX reserves
massive foreign-currency inflows
₹10.3 lakh crore liquidity surplus
crude near $100
US 10-year yield near 5%
possible Fed tightening
possible BOJ tightening
and geopolitical instability around the Strait of Hormuz.
The RBI’s response is therefore becoming increasingly sophisticated.
It doesn’t necessarily need to raise the repo rate to tighten financial conditions.
It can use the liquidity sponge.
It can use VRRR.
It can manage the rupee through FX intervention.
It can influence liquidity through the CRR.
And it can allow the banking system to absorb some of the foreign-currency shock over time.
The real question for investors isn’t simply:
“Will RBI cut or hike rates?”
The better question is:
“How aggressively will the RBI neutralize the liquidity shock while defending the rupee against a world of $100 oil and 5% US Treasury yields?”
That is the chess game.
And for Nifty investors, the next major moves may come not from a single RBI announcement—but from the interaction between US inflation, crude oil, the yen, Treasury yields and India’s liquidity conditions.
In September 2026, the market is no longer trading on one story. It is trading on the collision of five stories at once.
Disclaimer
This article is for informational and educational purposes only and does not constitute financial, investment, trading, tax, or legal advice. The market data, economic figures, forecasts, opinions, and analysis presented in this article are based on publicly available information and may change without notice.
The discussion of the RBI, Nifty 50, US Treasury yields, crude oil, FII/DII flows, foreign-exchange reserves, the Indian rupee, Federal Reserve, Bank of Japan, and global markets is intended to explain market dynamics and should not be considered a recommendation to buy, sell, or hold any security, derivative, cryptocurrency, or other financial instrument.
Financial markets are subject to substantial volatility and risk. Past performance is not a guarantee of future results. Readers should conduct their own research and consider their financial goals, risk tolerance, and investment horizon before making any investment decision.
Where appropriate, investors should consult a SEBI-registered investment adviser or other qualified financial professional.
The author and publisher are not responsible for any financial loss, damage, or investment decision arising from the use of information contained in this article.
10 titles:
- RBI’s Hidden Chess Move: 5 Market Signals Every Nifty Investor Must Watch
- RBI Liquidity Strategy 2026: 5 Surprising Signals That Could Move Nifty
- RBI’s Big Liquidity Move: What ₹10.3 Lakh Crore Means for Nifty in 2026
- RBI vs Global Markets: 5 Hidden Risks Every Indian Investor Should Know
- Why RBI Is Absorbing ₹10 Lakh Crore: The Hidden Risk for Nifty Investors
- RBI’s Next Move Could Decide Nifty’s Direction: 5 Key Signals to Watch
- US Yields, $100 Oil & RBI Liquidity: 5 Forces Shaping Nifty in 2026
- RBI Liquidity Shock Explained: How VRRR, Rupee & Crude Could Impact Nifty
- The RBI’s Hidden Battle: Liquidity, Rupee, Crude Oil and Nifty Explained
- Nifty’s Next Big Move? RBI Liquidity, US Rates, Oil & FII Flows Hold the Key