
Introduction: Understanding the Changing Market Environment
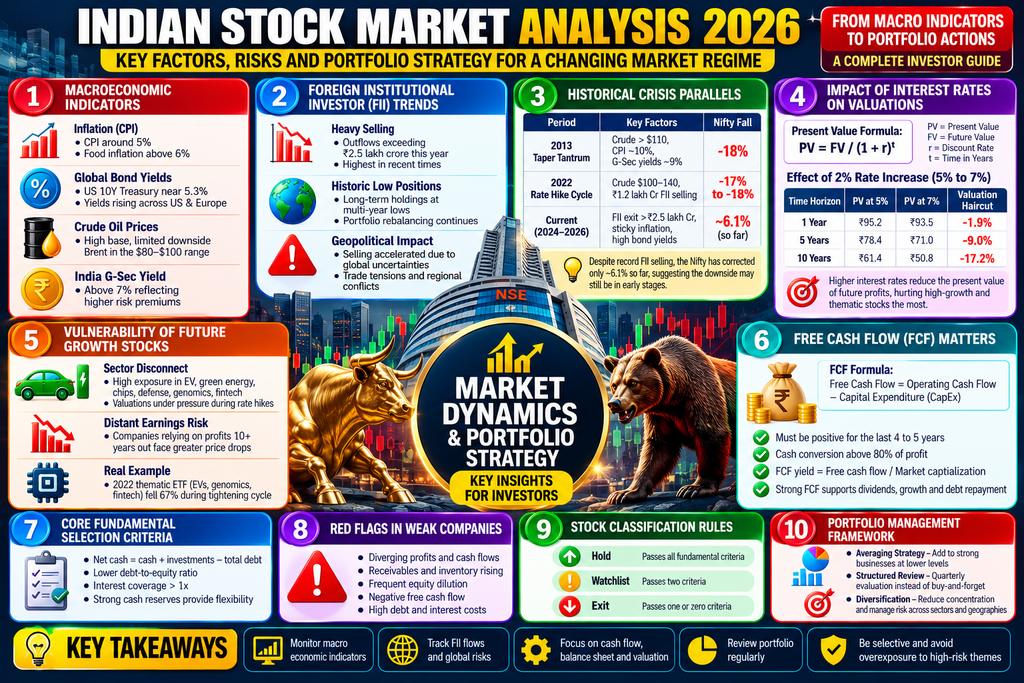
The Indian stock market is influenced by several interconnected forces: inflation, interest rates, foreign institutional investor (FII) flows, crude oil prices, currency movements, corporate earnings and stock valuations.
When global financial conditions become tighter, investors may reassess the prices they are willing to pay for future earnings. Companies with high debt, weak cash generation or expensive valuations can become more vulnerable to market corrections. Meanwhile, businesses with resilient balance sheets and sustainable cash flows may have greater flexibility to manage difficult economic conditions.
For investors, understanding these connections is essential. Instead of reacting to every market headline, a structured investment framework can help identify financial risks, evaluate business quality and distinguish short-term volatility from longer-term changes in company fundamentals.
This article examines seven important areas: macroeconomic indicators, FII selling, interest-rate sensitivity, cash-flow quality, balance-sheet strength, valuation discipline and practical portfolio management.
1. Macroeconomic Indicators: Inflation, Bond Yields and Crude Oil
Three important indicators for Indian equity investors are inflation, global bond yields and crude oil prices.
A. Inflation and purchasing power
Inflation measures the rate at which the prices of goods and services increase over time. Persistent inflation can affect household spending, business costs and monetary policy.
For example, if a company experiences a 10% increase in input costs but can increase selling prices by only 5%, its profit margins may come under pressure, assuming other factors remain unchanged.
Investors should monitor:
- Consumer Price Index (CPI) inflation.
- Food inflation and food-price volatility.
- Wholesale input prices.
- Corporate operating margins.
- Household consumption and demand trends.
The relationship between inflation and stock prices is not always straightforward. Companies with pricing power may pass higher costs to customers, while businesses operating in competitive industries may have less flexibility.
B. Global bond yields
Government bond yields influence borrowing costs, investment alternatives, and the discount rates used to value future cash flows.
When US Treasury yields rise, some international investors may reconsider the relative attractiveness of emerging-market assets. However, foreign investment decisions also depend on currency expectations, corporate earnings, valuations, liquidity and global risk appetite.
India’s government bond yields also matter because they influence domestic financing conditions and provide a reference point for assessing equity returns.
C. Crude oil prices
India imports a substantial share of its crude oil requirements, making global energy prices an important economic variable.
Higher crude prices can affect:
- The country’s import bill and current account.
- Currency stability.
- Transportation and manufacturing costs.
- Inflation and consumer purchasing power.
- Profit margins in aviation, paints, chemicals and logistics.
The impact differs across industries. An oil price increase may benefit some producers while creating challenges for companies that use energy as a major input.
Investor takeaway: Evaluate inflation, bond yields and crude oil together rather than relying on a single macroeconomic indicator.
2. FII Selling: How Foreign Investor Flows Affect Indian Equities
Foreign institutional investors can influence short-term market liquidity because they allocate capital across countries, sectors and asset classes.
When foreign investors sell Indian equities, the additional supply of shares can contribute to downward price pressure, particularly when domestic demand is insufficient to absorb the selling.
However, FII selling does not automatically mean that the underlying businesses have deteriorated.
Why foreign investors may reduce exposure
Some potential drivers include:
- Currency depreciation: A weaker rupee can reduce dollar-denominated returns when currency exposure is unhedged.
- Higher global yields: US Treasury yields may change the relative attractiveness of competing investments.
- Valuation differences: Foreign investors may reduce exposure to markets they consider expensive relative to alternatives.
- Geopolitical uncertainty: International conflicts and trade disruptions can lead to changes in risk appetite.
- Portfolio rebalancing: Global funds may change allocations because of investment mandates, redemptions or changes in regional exposure.
FII versus DII flows
Domestic institutional investors, including mutual funds, insurance companies and other institutions, can absorb some foreign selling. But domestic buying does not guarantee that market prices will rise.
| Indicator | What it tells investors | Important limitation |
|---|---|---|
| FII net flows | Foreign investors’ net buying or selling | Does not directly measure company fundamentals |
| DII net flows | Domestic institutions’ net buying or selling | Positive flows cannot guarantee a market recovery |
| Trading volume | Intensity of market participation | High volume alone does not establish direction |
| Sector-level flows | Areas attracting or losing institutional interest | Flow data may not explain the underlying motive |
| Currency movement | Changes in the rupee’s external value | Many factors influence currency movements |
How investors should interpret FII data
Suppose foreign institutions sell ₹10,000 crore of equities over a particular period while domestic institutions purchase ₹8,000 crore.
The combined institutional flow would be negative ₹2,000 crore, assuming the figures cover the same period and comparable markets.
This example illustrates net flows, not a prediction of market direction.
Investors should examine flow data alongside earnings, valuation, price action, liquidity and company-specific information.
Investor takeaway: FII data can help explain market pressure, but it should not be used as a standalone buy or sell signal.
3. Interest Rates and Stock Valuations: Why Future Earnings Matter
One important connection in equity valuation is the relationship between interest rates and the present value of future cash flows.
The simplified present-value formula is:
\[ PV=\frac{FV}{(1+r)^t} \]
Where:
- \(PV\) is present value.
- \(FV\) is a future cash flow.
- \(r\) is the discount rate.
- \(t\) is the number of periods until the cash flow occurs.
Consider a hypothetical ₹100 payment expected five years from now.
| Discount rate | Present value |
|---|---|
| 5% | ₹78.35 |
| 7% | ₹71.30 |
| 9% | ₹64.99 |
Illustrative calculation; the payment is assumed to occur once after five years.
As the discount rate increases, the present value of the future payment decreases.
This relationship helps explain why stocks valued largely on distant future earnings can experience valuation pressure when interest rates or required returns rise.
Which companies may be more sensitive?
High-growth companies: Their valuations may depend heavily on earnings expected many years into the future.
Highly leveraged businesses: Higher borrowing costs can increase interest expenses and reduce profits.
Real estate companies: Financing costs can affect developers, homebuyers, and housing demand.
Automobile companies: Higher financing costs may influence vehicle affordability and sales.
Capital-intensive companies: Businesses requiring substantial investment may face higher project costs.
The actual impact depends on each company’s debt structure, pricing power, cash flow, growth prospects, and competitive position.
Investor takeaway: Evaluate a company’s valuation and financing structure together. A strong growth story does not eliminate valuation risk.
4. Free Cash Flow: Measuring the Quality of Corporate Earnings
Reported net profit is an important measure, but it does not necessarily indicate how much cash a company generates.
Free cash flow is commonly calculated as:
\[ FCF=Operating\ Cash\ Flow-Capital\ Expenditure \]
For example, consider a hypothetical company with the following annual figures.
| Financial metric | Amount |
|---|---|
| Revenue | ₹1,000 crore |
| Net profit | ₹100 crore |
| Operating cash flow | ₹150 crore |
| Capital expenditure | ₹60 crore |
| Free cash flow | ₹90 crore |
In this example, the company generates ₹90 crore in free cash flow after capital expenditure.
That cash may help finance future investment, repay debt, distribute dividends or build liquidity, depending on management’s decisions and other financial obligations.
What investors should examine
Operating cash flow: Is the business converting sales and earnings into cash?
Free cash flow consistency: Is free cash flow positive over multiple years, or does it fluctuate significantly?
Receivables: Are customers paying on time, or are outstanding amounts increasing rapidly?
Inventory: Is inventory growing faster than sales?
Capital expenditure: Is the company investing in productive capacity, maintenance,e or projects with uncertain returns?
Working capital: Are changes in receivables, inventory and payables affecting cash generation?
A single year of weak free cash flow does not necessarily indicate a problem. Growing companies may need substantial investment, and seasonal businesses can experience significant working-capital fluctuations.
The key is to understand the reason behind the numbers and assess whether the pattern is sustainable.
Investor takeaway: Compare net profit with operating cash flow and capital expenditure over several years before concluding that a business has strong earnings quality.
5. Cash Reserves and Debt: Evaluating Financial Resilience
A company with manageable debt and sufficient liquidity may have more flexibility during an economic slowdown than a company dependent on frequent refinancing.
However, debt is not inherently negative. Many businesses use borrowing to finance productive assets, and the appropriate debt level varies by industry.
Net cash calculation
\[ Net\ Cash=Cash+Liquid\ Investments-Total\ Debt \]
Consider two hypothetical businesses.
| Financial measure | Company A | Company B |
|---|---|---|
| Cash and liquid investments | ₹500 crore | ₹150 crore |
| Total debt | ₹300 crore | ₹600 crore |
| Net cash/(net debt) | ₹200 crore | -₹450 crore |
Company A has a net cash position of ₹200 crore, while Company B has net debt of ₹450 crore.
This does not establish that Company A is a better investment. Investors must also consider earnings stability, industry conditions, debt maturities, working capital and capital allocation.
Five financial indicators worth monitoring
- Debt-to-equity ratio: Measures debt relative to shareholder equity.
- Interest coverage ratio: Evaluates the ability to cover interest expenses from operating earnings.
- Current ratio: Compares current assets with current liabilities.
- Operating cash flow: Shows cash generated by core business operations.
- Debt maturity schedule: Identifies upcoming repayment and refinancing requirements.
For banks and financial institutions, traditional industrial-company debt ratios are often less informative because borrowing and lending are central to their business models. Sector-specific measures are more appropriate.
Investor takeaway: Financial resilience depends on more than cash reserves. Debt obligations, recurring cash generation, and access to funding all matter.
6. Stock Valuation: Avoiding Value Traps and Overpaying for Growth
A stock can be an excellent business and still deliver disappointing returns if its purchase price is too high.
Similarly, a stock trading at a low valuation may be inexpensive for a good reason, such as declining demand, weak management execution, or structural industry disruption.
Understanding the P/E ratio
The price-to-earnings ratio is calculated as:
\[ P/E=\frac{Share\ Price}{Earnings\ Per\ Share} \]
Suppose a company trades at ₹400 per share and earns ₹20 per share annually.
Its P/E ratio is:
\[ P/E=\frac{400}{20}=20 \]
The company is trading at 20 times its annual earnings.
This number becomes more useful when compared with the company’s historical valuation, expected earnings growth, industry peers, profitability and financial risk.
What about the PEG ratio?
The price/earnings-to-growth ratio attempts to relate valuation to expected earnings growth.
A simplified calculation is:
\[ PEG=\frac{P/E\ Ratio}{Annual\ Earnings\ Growth\ Rate} \]
For example, a P/E ratio of 20 and expected annual earnings growth of 10% would produce a PEG ratio of 2.0 under this convention.
A lower PEG ratio does not automatically mean a stock is undervalued. Earnings forecasts can be inaccurate, and the calculation does not fully account for capital requirements, debt, cash-flow quality or business risk.
Common valuation mistakes
- Assuming every falling stock is cheap.
- Using past earnings without considering future changes.
- Comparing companies from very different industries.
- Ignoring debt and cash generation.
- Treating analyst forecasts as guaranteed outcomes.
- Buying a stock solely because its historical price was much higher.
Investor takeaway: A valuation assessment should consider the business, the financial statements, expected growth, and the risks already reflected in the share price.
7. Financial Red Flags: Identifying Potentially Weak Businesses
Investors can improve their research process by identifying financial patterns that warrant additional investigation.
| Potential warning sign | Why it matters | What to investigate |
|---|---|---|
| Profit rises but operating cash flow weakens | Earnings may not be translating into cash | Receivables, inventory and accounting adjustments |
| Debt grows faster than operating earnings | Repayment capacity may weaken | Interest coverage and debt maturities |
| Repeated equity dilution | Existing shareholders’ ownership may decline | Use of proceeds and returns on new capital |
| Receivables grow faster than revenue | Customer collections may be slowing | Credit terms and overdue balances |
| Inventory increases sharply | Demand may be weakening or stock may be accumulating | Sales trends, write-downs and inventory turnover |
| Persistent negative free cash flow | The business may require external financing | Investment plans, funding needs and cash runway |
| Margins decline over several periods | Competitive or cost pressures may be increasing | Pricing power, input costs and market share |
None of these indicators proves fraud or financial distress on its own. Seasonal effects, rapid growth, acquisitions and industry characteristics can produce similar patterns.
Investors should compare several reporting periods and review company disclosures before concluding.
8. Portfolio Management Framework: Turning Research into a Repeatable Process
A structured portfolio process helps investors connect company research with their financial objectives.
Step 1: Define the investment objective
Determine whether the portfolio is designed for long-term wealth creation, income generation, capital preservation, or short-term trading.
Different objectives require different risk limits and time horizons.
Step 2: Separate core holdings from tactical positions
Long-term investments and short-term trades should have separate entry criteria, risk controls and review schedules.
A short-term trading loss should not automatically determine the decision on a fundamentally different long-term investment.
Step 3: Set position-size limits
Consider how much capital is exposed to each company, industry and common economic risk.
For example, owning several companies from the same cyclical industry may create more concentration than the number of holdings suggests.
Step 4: Establish a review schedule
Review quarterly earnings, balance-sheet changes, valuation, corporate announcements and the original investment thesis.
A review does not require a transaction every time. Sometimes the appropriate action is to gather more information.
Step 5: Create predefined risk rules
Investors should understand their ability to withstand losses, the consequences of leverage and the liquidity of their holdings.
Short-term traders may use stop-loss orders, but gaps, low liquidity and rapid price movements can cause actual execution prices to differ from expected levels.
Step 6: Document decisions
Record why an investment was made, which assumptions support the thesis and what evidence would cause it to be reassessed.
Written criteria can help reduce decisions driven by fear, overconfidence or market rumours.
9. Illustrative Portfolio Risk Audit
The following example demonstrates how a hypothetical ₹1,00,000 equity portfolio could be reviewed. It is not a recommended allocation.
| Holding category | Illustrative amount | Review focus |
|---|---|---|
| Large established companies | ₹40,000 | Earnings stability, valuation and balance sheet |
| Growth companies | ₹25,000 | Future earnings assumptions and cash flow |
| Cyclical companies | ₹15,000 | Economic sensitivity and debt |
| Other sector holdings | ₹10,000 | Diversification and business-specific risks |
| Cash available outside the equity portfolio | ₹10,000 | Liquidity needs and financial objectives |
| Total capital | ₹1,00,000 |
Actual diversification depends on the businesses owned, not simply the number of holdings or labels assigned to them. Several companies can share the same underlying risks.
Investors should also consider emergency savings, existing debt, time horizon, tax obligations and whether the capital can remain invested through a market decline.
10. Three Market Scenarios Investors Can Monitor
Rather than predicting an exact market bottom, investors can prepare for different economic conditions.
Scenario A: Improving conditions
Inflation moderates, global yields stabilise, crude oil prices ease and earnings expectations improve.
Areas to monitor: earnings upgrades, credit growth, liquidity and valuation changes.
Scenario B: Continued uncertainty
Inflation and energy costs remain elevated, institutional flows fluctuate and companies report mixed earnings.
Areas to monitor: cash-flow quality, margins, sector concentration and borrowing costs.
Scenario C: Deteriorating conditions
Inflation accelerates, global yields rise further, currency pressure increases,s and earnings estimates weaken.
Areas to monitor: leverage, liquidity, refinancing requirements and exposure to cyclical demand.
These are conditional scenarios, not predictions or assigned probabilities. Market outcomes depend on the interaction of many variables, and no single indicator can establish the direction of future stock prices.
Conclusion: Focus on Financial Strength, Not Just Market Direction
The Indian stock market responds to domestic economic conditions, global financial markets, institutional flows and company-specific developments.
Inflation, crude oil prices and bond yields can influence financing costs and valuation assumptions. FII selling can affect liquidity and sentiment, while DII participation can change the balance of demand. However, neither institutional flows nor macroeconomic headlines can determine the value of every company.
For long-term investors, the more durable research process is to examine cash-flow quality, balance-sheet strength, competitive advantages, valuation discipline and portfolio concentration.
The objective is not to predict every market movement. It is to understand the risks within the portfolio and make decisions consistent with one’s financial circumstances and investment horizon.
Key lessons:
- Monitor inflation, crude oil, currency movements, TS, and bond yields together.
- Treat institutional flow data as context rather than a standalone trading signal.
- Understand how interest rates affect discounted future cash flows.
- Compare reported profits with operating cash flow and capital expenditure.
- Examine debt, liquidity and refinancing needs.
- Avoid assuming that a low P/E ratio guarantees an undervalued stock.
- Review company fundamentals and portfolio concentration regularly.
A repeatable research process cannot eliminate market risk, but it can make investment decisions more systematic and transparent.
Frequently Asked Questions (FAQs)
1. What factors influence the Indian stock market?
Important factors include corporate earnings, economic growth, inflation, interest rates, foreign and domestic institutional flows, crude oil prices, currency movements, geopolitical developments and equity valuations.
2. Does FII selling always cause the market to fall?
No. FII selling can contribute to market pressure, but price movements also depend on domestic investor demand, earnings expectations, liquidity, valuations and other market participants.
3. Why can higher interest rates affect stock prices?
Higher rates can increase borrowing costs and raise the discount rate applied to future cash flows. The impact varies depending on company debt, profitability, growth expectations and valuation.
4. What is free cash flow in stock analysis?
Free cash flow is commonly calculated as operating cash flow minus capital expenditure. It helps investors assess the cash available after investment in business assets.
5. How can investors identify a potentially weak balance sheet?
Review debt, cash reserves, interest coverage, short-term liabilities, operating cash flow, and debt maturities. The interpretation should reflect the company’s industry and business model.
6. Is a low P/E ratio always attractive?
No. A low P/E may reflect undervaluation, but it may also indicate declining earnings, weak growth prospects or elevated business risks.
7. How often should a long-term portfolio be reviewed?
A quarterly review is a practical starting point for many investors. Additional reviews may be necessary after significant earnings changes, corporate announcements or changes in personal financial circumstances.
8. Can diversification eliminate investment risk?
No. Diversification can reduce the impact of company-specific risks, but it cannot eliminate market-wide declines, liquidity risk or losses caused by correlated investments.
Disclaimer
This article is intended for educational and informational purposes only. It does not constitute investment advice, financial advice, a recommendation to buy or sell securities, or a guarantee of future market performance. Numerical examples are illustrative unless explicitly identified as verified data. Macroeconomic indicators, market prices, institutional flows, and company financial statements should be independently verified against current official sources before publication or investment use. Readers should conduct their own research and consult a qualified financial advisor when appropriate. Investments in securities are subject to market risks, including possible loss of capital.