The $150 Barrel: Why the Global Energy Map Is Redrawing Itself
Introduction: Is the Global Energy System Entering a New Risk Era?
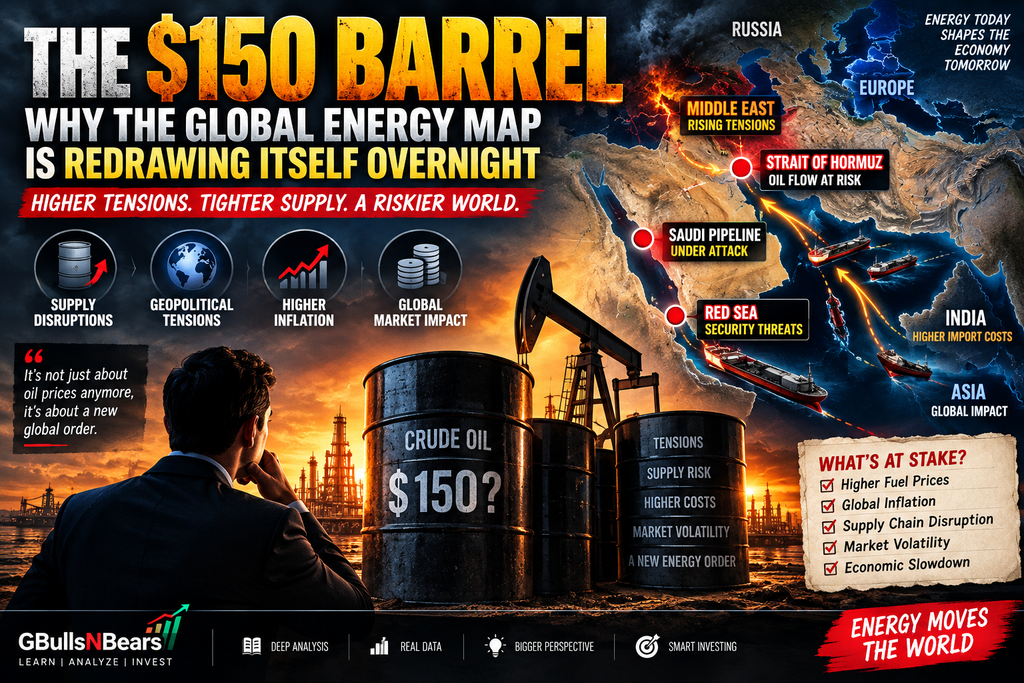
The global oil market is facing one of its most significant supply-chain challenges in recent years. Disruptions around the Strait of Hormuz, Saudi Arabia’s East-West pipeline and the Red Sea shipping corridor have increased concerns about energy security, transportation costs and inflation.
Brent crude briefly moved above $110 per barrel during September, following attacks on energy infrastructure and concerns about restricted shipping routes. Prices subsequently eased as Saudi Arabia began working toward the partial restoration of its East-West pipeline and diplomatic developments raised hopes of improved regional supply flows.
This creates a complicated market situation:
- Supply disruptions are increasing the risk premium.
- Alternative export routes are under pressure.
- Oil prices remain sensitive to geopolitical headlines.
- Diplomatic developments can trigger rapid price reversals.
- A prolonged disruption could create further upward pressure.
A move toward $150 crude oil is a high-risk scenario, not a confirmed forecast. Bank of America has warned that oil could exceed $150 if supply constraints worsen, while its reported year-end Brent forecast was lower at $95 per barrel. This distinction is important: a stress scenario is not the same as a base-case price target.
1. The Triple Chokepoint: Pressure on Global Oil Transit Routes
The global oil transportation network depends on several strategic maritime and land-based routes. When multiple routes face disruption at the same time, the market can experience higher shipping costs, longer delivery times, and tighter regional supply.
A. Strait of Hormuz
The Strait of Hormuz is one of the world’s most important energy transit routes. Disruptions in the waterway can affect crude oil and petroleum product flows from major Gulf producers.
Recent reports indicated that shipping through the strait had slowed substantially during the conflict, while subsequent developments suggested that some traffic and export activity had begun to recover.
Why Hormuz matters
- It connects major Gulf oil producers with international buyers.
- Restrictions can increase tanker and insurance costs.
- Delays can affect refiners that depend on specific crude grades.
- A prolonged disruption can increase the global risk premium.
The exact volume affected will vary depending on the route, vessel movements, export diversions,s and the duration of any restrictions.
B. Bab el-Mandeb and the Red Sea
The Bab el-Mandeb Strait connects the Red Sea with the Gulf of Aden and is an important route for global trade and energy shipments.
Reports have described growing security risks in the Red Sea region, including attacks and territorial developments involving Houthi forces. These developments create uncertainty for shipping companies and may encourage vessels to use longer alternative routes.
Potential economic effects
- Longer shipping journeys
- Higher freight and insurance costs
- Increased delivery times
- Higher regional fuel costs
- Additional pressure on European and Asian refiners
The Red Sea is not a perfect substitute for every crude shipment that would otherwise pass through Hormuz. The availability of alternative routes depends on infrastructure, vessel capacity, security conditions and the type of oil being transported.
C. Saudi Arabia’s East-West Pipeline
Saudi Arabia’s East-West pipeline is a major alternative route designed to transport crude from the country’s eastern oil-producing region toward the Red Sea.
The pipeline was temporarily shut down after attacks damaged pumping stations. Reuters reported that the pipeline normally transports approximately 4–5 million barrels per day in recent months, while other reports describe a larger overall design capacity. The distinction between actual throughput and maximum capacity is important.
Saudi Arabia subsequently began working toward partial restoration, and reports indicated that the pipeline could return to full capacity within approximately six weeks.
Why the pipeline is strategically important
The pipeline provides Saudi Arabia with an alternative to shipping all crude through the Strait of Hormuz. If both maritime and land-based routes are disrupted, the market may face tighter logistics and greater regional supply uncertainty.
However, the pipeline should not be described as the only global safety valve. Other routes, storage facilities, alternative suppliers and production adjustments can provide partial relief, although their effectiveness may be limited during a simultaneous disruption.
2. Crude Oil Price Data: From $110 to the $150 Stress Scenario
Recent price movements
Brent crude rose above $110 per barrel during September as concerns about Middle East supply disruptions intensified. On September 14, Brent was reported near $106–$108 per barrel after the Saudi pipeline shutdown and further shipping concerns.
Oil prices later declined as:
- Saudi Arabia signaled progress toward pipeline restoration.
- Some alternative export arrangements were used.
- Diplomatic discussions raised hopes of de-escalation.
- Traders reduced some of the immediate supply-disruption premium.
On September 23, reports placed Brent near $100 per barrel, illustrating the market’s sensitivity to geopolitical and supply-related headlines.
Three crude oil price scenarios
| Scenario | Possible market conditions |
|---|---|
| Base or stabilisation scenario | Pipeline restoration and improved shipping reduce supply concerns |
| Stress scenario | Prolonged disruption keeps Brent above $110–$120 |
| Extreme scenario | Multiple routes remain impaired, ed and additional infrastructure damage pushes prices toward $150 |
These scenarios are illustrative. They are not guaranteed forecasts or precise probabilities.
What could push crude toward $150?
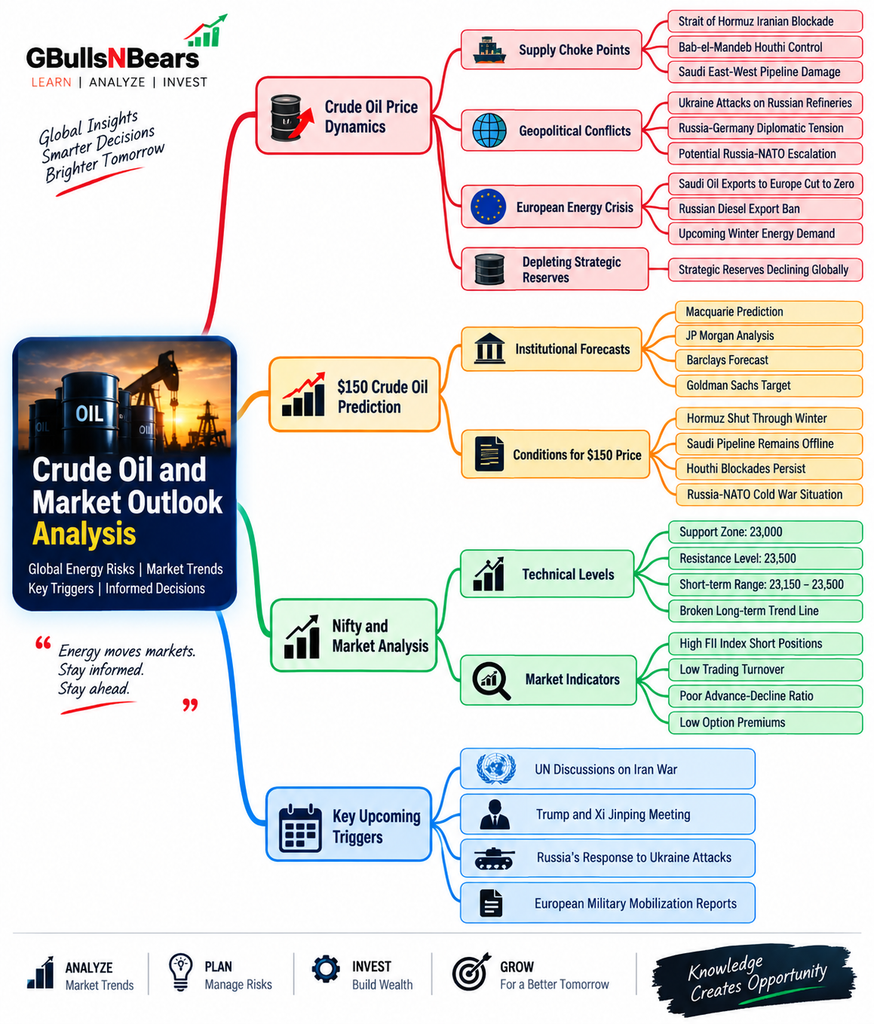
A move toward $150 could require a combination of factors, such as:
- Prolonged restrictions around the Strait of Hormuz
- Further damage to energy infrastructure
- Continued disruption in Red Sea shipping
- Reduced availability of alternative crude supplies
- Declining commercial and strategic inventories
- Escalation involving additional regional or international actors
Bank of America has discussed the possibility of oil exceeding $150 if supply constraints intensify. However, the same reporting also identified a lower forecast under less severe conditions.
Key point: $150 crude is a potential extreme-risk scenario, not an established market consensus.
3. Europe’s Energy Challenge: Supply Disruptions and Refinery Pressure
Europe’s energy system remains exposed to changes in crude supply, shipping routes and refinery economics. When a major supplier interrupts deliveries, refiners must search for alternative crude grades and transportation arrangements.
Saudi Aramco and October crude deliveries
Reports indicated that Saudi Aramco informed at least two European refining customers that they would receive no crude in October under their regular term arrangements after the East-West pipeline disruption. Reuters noted that the report was based on information reported by Bloomberg and could not independently verify all details.
This development does not mean that all European refineries will run out of oil. Refiners can attempt to source alternative supplies, including crude from other regions. However, replacement supplies may involve:
- Higher transportation costs
- Different crude quality
- Higher procurement expenses
- Refinery adjustments
- Increased competition for available cargoes
Why European refiners are vulnerable
Refineries are designed to process particular crude grades efficiently. Replacing a disrupted supply is not always a simple one-for-one transaction.
The overall impact will depend on:
- Alternative crude availability
- Refinery configuration
- Storage levels
- Shipping costs
- Duration of the disruption
- Government and industry responses
4. The Strategic Reserve Question: Is the World Running Out of Its Buffer?
Strategic petroleum reserves and commercial inventories act as buffers during supply disruptions. They can help reduce immediate shortages, but they are not unlimited.
It would be inaccurate to claim that global strategic reserves are already approaching zero without verified inventory data across the relevant countries. A more defensible concern is that prolonged supply disruptions can reduce inventory flexibility and increase the market’s sensitivity to new shocks.
Why inventories matter
When inventories are relatively comfortable:
- Refiners have more flexibility.
- Temporary supply disruptions may be absorbed more easily.
- Price spikes may be less severe.
When inventories are tight:
- Buyers may compete for replacement cargoes.
- Freight and insurance costs can rise.
- Small disruptions may have a larger price impact.
- Governments may consider reserve releases or demand-management measures.
India’s energy security
India can be affected by regional energy disruptions through crude import costs, shipping routes, insurance premiums and currency movements.
Potential policy responses include:
- Diversifying crude suppliers
- Expanding strategic petroleum storage
- Strengthening port infrastructure
- Developing alternative energy partnerships
- Improving energy efficiency
- Increasing renewable and domestic energy capacity
Reports have highlighted the potential role of UAE and Oman in helping India explore alternative energy routes and strengthen supply resilience.
5. Civil Defence and War Readiness: What Can Be Concluded?
The original article connects civil-defence preparations in Switzerland, Estonia and the United Kingdom with the conclusion that global energy security has collapsed.
Such a conclusion would be too broad without reliable evidence linking each government’s specific preparedness measures directly to the current oil-supply situation.
Governments may increase emergency preparedness because of several risks:
- Cyberattacks
- Military conflict
- Infrastructure disruption
- Natural disasters
- Energy shortages
- Supply-chain vulnerabilities
A more useful interpretation
Civil-defence planning can indicate that governments are taking wider security risks seriously. It does not automatically prove that a global energy collapse or broader war is inevitable.
Investors should distinguish between:
- Documented government preparedness measures
- Official statements about security risks
- Analyst interpretations
- Speculative predictions about future conflict
This distinction is especially important when financial decisions are based on geopolitical news.
6. Impact on India: Why Higher Crude Could Pressure the Economy
India is sensitive to crude oil prices because imported energy affects the country’s external balance, inflation outlook and corporate costs.
Major transmission channels
1. Import bill
Higher crude prices can increase the amount India spends on energy imports, particularly if import volumes remain stable.
2. Indian rupee
A larger import bill can contribute to pressure on the rupee, although exchange rates also depend on capital flows, interest-rate differentials, global dollar demand and central-bank policy.
3. Inflation
Higher fuel and transportation costs can affect the price of goods and services. The final impact depends on domestic fuel pricing, government policies and how businesses manage costs.
4. Corporate margins
Oil-sensitive industries may face higher operating expenses, especially if they cannot pass the additional costs to customers.
5. Consumer spending
Higher fuel and transportation expenses may reduce disposable income and affect discretionary spending.
Indian sectors to monitor
| Sector | Possible impact from higher crude |
|---|---|
| Aviation | Higher jet-fuel costs |
| Paints | Higher input costs |
| Tyres | Raw-material cost pressure |
| Logistics | Increased fuel and freight expenses |
| Chemicals | Feedstock and energy costs |
| Consumer companies | Potential pressure on consumer demand |
| Oil marketing companies | Margin and pricing-policy sensitivity |
| Renewable energy | Potential long-term strategic interest |
The actual impact varies by company. Investors should examine cost structure, pricing power, debt, hedging policies and operating margins.
7. Impact on Global Markets and Indian Equities
Crude oil prices can affect global markets through inflation, bond yields, corporate costs and monetary policy expectations.
Possible global market reactions
If oil prices rise sharply and remain elevated:
- Inflation expectations may increase.
- Central banks may delay interest-rate reductions.
- Bond yields could face upward pressure.
- Energy stocks may outperform some other sectors.
- Transportation and consumer sectors may face margin pressure.
- Emerging-market currencies may become more volatile.
However, the market response is not uniform. Energy-producing economies and companies may benefit from higher prices, while importing economies and energy-intensive businesses may face greater pressure.
What it means for Nifty 50
For Indian equities, investors should monitor:
- Nifty support and resistance levels
- FII and DII flows
- USD/INR movement
- India VIX
- Crude oil futures
- Corporate earnings estimates
- RBI communication
- Market breadth
A rise in crude oil does not automatically mean that Nifty will crash. The effect depends on the severity and duration of the shock, as well as how much risk is already reflected in valuations.
8. The $150 Oil Scenario: Four Risks to Watch
The following factors could increase the likelihood of an extreme oil-price scenario if they occur together.
1. Prolonged Strait of Hormuz Disruption
Extended shipping restrictions could reduce the availability of crude reaching international buyers.
2. Extended Pipeline Downtime
Delays in restoring Saudi Arabia’s East-West pipeline could limit an important alternative export route.
3. Additional Shipping and Infrastructure Attacks
New attacks could increase freight costs, insurance premiums, and supply uncertainty.
4. Wider Geopolitical Escalation
A broader conflict involving additional countries could increase the risk of further export and transportation disruptions.
These factors would not necessarily occur together. The market may also experience de-escalation, alternative supply arrangements,s and partial infrastructure restoration.
9. How Investors Should Track the Oil Market
Investors should avoid relying on headlines alone. A structured monitoring framework can help distinguish a temporary price spike from a sustained energy shock.
Daily monitoring checklist
| Indicator | Why it matters |
|---|---|
| Brent crude | Global benchmark for oil prices |
| WTI crude | US crude-price benchmark |
| Strait of Hormuz traffic | Indicates shipping disruption |
| Saudi pipeline status | Tracks alternative export capacity |
| Tanker freight rates | Shows transportation pressure |
| Oil inventories | Measures available supply buffer |
| USD/INR | Indicates currency pressure |
| India VIX | Measures expected market volatility |
| FII flows | Shows foreign investor activity |
| RBI communication | Indicates inflation and monetary-policy risks |
Questions investors should ask
- Is the oil-price increase caused by a temporary headline or a physical supply shortage?
- Are alternative export routes operating?
- Is the pipeline restoration progressing?
- Are shipping and insurance costs rising?
- Are inventories declining?
- Are central banks changing their inflation outlook?
- Are Indian companies revising their earnings guidance?
10. What Could Prevent Crude Oil From Reaching $150?
The oil market is exposed to upside risks, but several factors could limit or reverse a price surge.
Possible stabilising factors
- Partial restoration of Saudi pipeline operations
- Increased shipments through alternative routes
- Diplomatic progress involving regional governments
- Reduced restrictions on shipping
- Strategic reserve releases
- Lower global oil demand
- Increased production from alternative suppliers
- A stronger US dollar or weaker demand expectations
Recent reports indicated that Saudi Arabia was testing its East-West pipeline and that oil prices declined as supply-restoration expectations improved.
This demonstrates why investors should avoid treating the $150 scenario as inevitable.
Conclusion: The Energy Market Is Vulnerable, but $150 Is Not Guaranteed
The global energy market is experiencing a period of elevated geopolitical and infrastructure risk. Disruptions involving the Strait of Hormuz, Red Sea shipping and Saudi Arabia’s East-West pipeline have increased uncertainty around crude supply, transportation costs and energy security.
Brent crude has recently traded above $100 and moved above $110 during periods of heightened disruption. A further increase toward $150 remains a possible stress scenario if multiple supply routes remain impaired and the conflict escalates. However, the reported $150 warning should be treated as a conditional risk scenario rather than a guaranteed price target or universal institutional consensus.
For India, the most important risks include:
- Higher crude import costs
- Pressure on the rupee
- Inflationary pressure
- Higher transportation expenses
- Reduced corporate margins
- Potential changes in monetary-policy expectations
The critical question is not simply whether oil will reach $150. It is whether the global energy system can restore enough transportation capacity, alternative supply and inventory flexibility to absorb future disruptions.
The global energy map is changing, but investors should separate verified supply-chain developments from speculation and prepare for multiple possible outcomes.
Frequently Asked Questions
1. Can crude oil reach $150 per barrel?
Yes, it is a possible extreme-risk scenario if supply disruptions worsen significantly. Bank of America has warned that oil could exceed $150 under tighter supply conditions, but this is not a confirmed forecast.
2. Why is the Strait of Hormuz important?
The Strait of Hormuz is a major energy transit route. Disruptions can affect crude flows, tanker costs, insurance premiums and delivery times.
3. Has Saudi Arabia’s East-West pipeline been restored?
Reports indicate that Saudi Arabia began testing and working toward the partial restoration of the pipeline after attacks caused disruptions. The timing and volume of full restoration remain important market variables.
4. How can higher crude prices affect India?
Higher crude prices can increase India’s import expenditure, put pressure on the rupee, raise transportation costs and affect inflation and corporate profitability.
5. Will Nifty 50 crash if oil reaches $150?
A sharp rise in oil prices could increase pressure on Indian equities, but a market crash is not guaranteed. The outcome would depend on the duration of the oil shock, earnings, valuations, monetary policy and investor flows.
6. What should investors monitor during an oil-price shock?
Investors should monitor Brent crude, shipping routes, pipeline restoration, oil inventories, USD/INR, FII flows, RBI communication and corporate earnings revisions.
Disclaimer
This article is provided for educational and informational purposes only and does not constitute financial, investment, trading, legal or geopolitical advice. Oil prices, geopolitical developments and market conditions can change rapidly. Some future scenarios discussed are conditional and uncertain. Readers should independently verify information, consult reliable official sources and consider their individual risk tolerance before making investment decisions.
Top 10 SEO Titles
- Could Oil Reach $150? Global Energy Crisis and Middle East Supply Risks Explained
- $150 Crude Oil Scenario: Strait of Hormuz Disruption and Global Market Impact
- Crude Oil at $150? 5 Global Energy Risks Every Investor Should Watch in 2026
- Global Oil Crisis 2026: How Middle East Tensions Could Push Crude Toward $150
- Why Oil Prices Could Surge to $150: Hormuz, Saudi Pipeline and Red Sea Risks
- $150 Oil Price Warning: How a Global Energy Shock Could Impact India
- Strait of Hormuz Crisis: Could Supply Disruptions Trigger a $150 Oil Shock?
- Crude Oil Outlook 2026: Global Supply Risks, Energy Security and Market Impact
- Oil Price Surge Alert: 4 Geopolitical Risks That Could Reshape Global Energy Markets
- The $150 Oil Scenario: How Middle East Conflict Could Affect India and Global Markets