
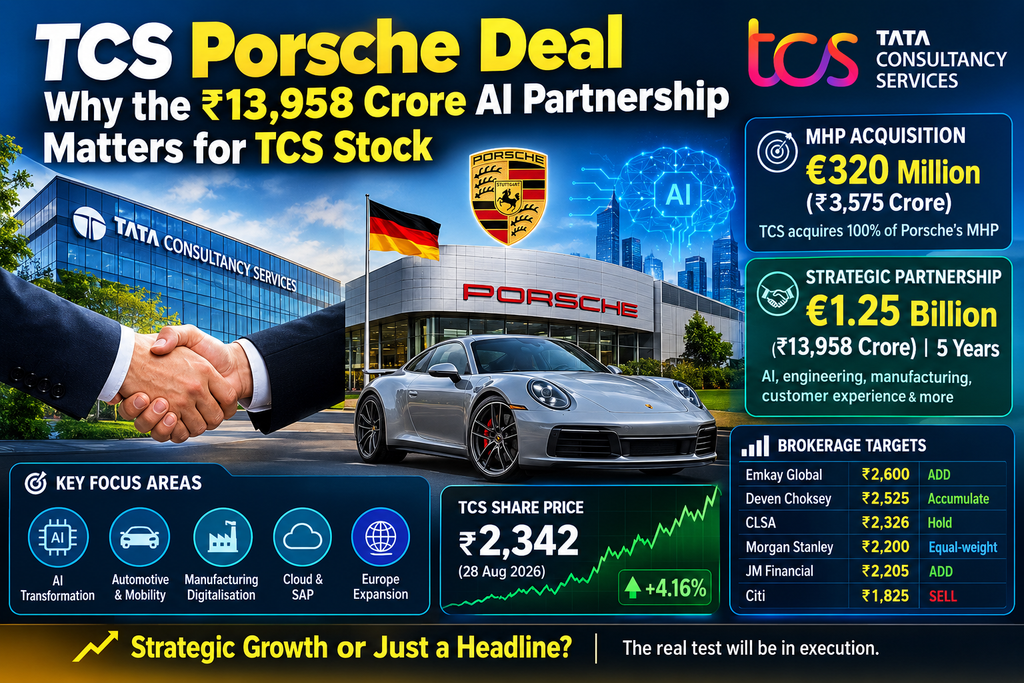
Tata Consultancy Services (TCS) has made one of its most strategically important moves in recent years by acquiring 100% of MHP Management- und IT-Beratung GmbH, Porsche’s Germany-based management and IT consulting subsidiary.
The transaction is valued at approximately €320 million, or around ₹3,575 crore, while Porsche has simultaneously entered into a five-year strategic partnership with TCS worth €1.25 billion, approximately ₹13,967 crore.
But the bigger question for investors is not simply how large the deal is.
The real question is:
Can this Porsche partnership change TCS’s growth trajectory, or is it mainly a strategic deal with limited near-term earnings impact?
The answer is somewhere in between.
1. What Exactly Did TCS Buy?
There are actually two transactions hidden inside the headline.
Deal No. 1 — MHP Acquisition
TCS will acquire 100% of MHP for:
€320 million
≈ ₹3,575 crore
MHP specialises in:
- Automotive consulting
- AI
- Digital transformation
- SAP
- Manufacturing digitalisation
- Connected mobility
- Software-defined mobility
The transaction remains subject to regulatory and antitrust approvals and is expected to close in the coming months.
Deal No. 2 — Porsche Strategic Partnership
Porsche has signed a five-year strategic agreement worth €1.25 billion with TCS and MHP.
The partnership will focus on AI transformation across:
- Engineering
- Manufacturing
- Operations
- Customer experience
- Enterprise transformation
- Automotive technology
- Software-defined mobility
TCS will also establish an AI Mobility Centre of Excellence for Porsche.
This is where the real strategic value lies.
2. TCS Did Not Just Buy Revenue — It Bought Positioning
MHP reported approximately €742 million of revenue in 2025 and has around 4,500 employees. However, its revenue had fallen from roughly €830 million in 2024 to €742 million in 2025.
That explains why the acquisition price looks relatively inexpensive.
TCS is paying approximately:
€320 million for a business with €742 million annual revenue.
That’s roughly 0.43× revenue.
This is an important number.
At first glance, the acquisition looks cheap.
But cheap revenue is not automatically high-quality revenue.
The real question is whether TCS can improve MHP’s margins and growth using its global delivery infrastructure.
3. The Discount Is the Most Interesting Part
The acquisition multiple is one of the biggest talking points.
Citi estimates that based on a potential FY28 revenue run-rate of €600–700 million and EBIT margins of 7–9%, the acquisition works out to roughly 5–8× EV/EBIT.
That suggests TCS is not paying an aggressive premium.
However, there is a reason the valuation is low.
MHP’s revenue is declining.
So the market has to decide whether:
TCS is buying a declining business cheaply
or
TCS is buying a strategic European automotive platform at a discounted valuation.
That distinction could ultimately determine whether the acquisition creates significant shareholder value.
4. Why Europe Matters for TCS
This is arguably more important than the immediate revenue contribution.
TCS already has a massive global footprint, but the acquisition gives it a stronger position in German automotive and industrial consulting.
MHP brings:
- German enterprise relationships
- Automotive domain expertise
- Consulting capabilities
- Manufacturing knowledge
- AI transformation capabilities
- SAP expertise
- Mobility technology
TCS brings:
- Global delivery scale
- AI capabilities
- Engineering talent
- Large enterprise relationships
- Offshore delivery infrastructure
The combination could potentially create a stronger Europe + Automotive + AI business.
TCS itself describes MHP’s capabilities as including business transformation, AI, SAP, manufacturing digitalisation and connected mobility.
5. Porsche Deal Could Be Bigger Than the Immediate Revenue
This is where investors need to look beyond the headline.
The €1.25 billion Porsche agreement provides TCS with a long-term relationship with one of Europe’s best-known automotive brands.
The strategic opportunity could extend beyond Porsche.
If TCS successfully demonstrates AI transformation across Porsche’s:
Engineering → Manufacturing → Operations → Customer Experience
then the company could potentially use that expertise to win additional European automotive and industrial clients.
So the acquisition could act as a reference platform.
That’s potentially more valuable than the initial MHP revenue contribution.
6. TCS Stock Price: The Market Has Already Reacted
The market reaction has been interesting.
TCS closed at:
₹2,342 on August 28, 2026
The stock gained approximately:
4.16% in one session
with volume of about 4.05 million shares.
That is significant because the stock had been under substantial pressure earlier in 2026.
The stock was around ₹2,284 on August 24 when the Porsche deal was announced and subsequently moved to ₹2,342 by August 28.
So the market initially interpreted the deal positively.
But the bigger question is whether this is the beginning of a sustained reversal.
7. TCS’s Bigger Problem: Growth
This is the part investors should not ignore.
TCS’s Q1 FY27 results showed:
- Revenue: $7.624 billion
- YoY growth: 2.7% in USD
- Constant-currency growth: 0.4% QoQ
- Operating margin: 24.0%
- Net margin: 19.2%
- TCV: $9.5 billion
- Annualised AI revenue: $2.6 billion
- AI revenue growth: 13.6% QoQ
These numbers show something important.
TCS is not a company without growth.
Instead, the market is questioning how quickly growth can accelerate.
That’s why the Porsche deal matters.
8. AI Could Be the Real Long-Term Catalyst
TCS reported annualised AI revenue of $2.6 billion in Q1 FY27, up 13.6% quarter-on-quarter.
The Porsche agreement fits directly into this strategy.
Rather than simply selling traditional IT outsourcing, TCS is increasingly trying to position itself around:
AI + Engineering + Manufacturing + Consulting
That is important because generative AI is putting pressure on traditional IT-services models.
If TCS can move higher up the value chain—from writing code to helping clients redesign business processes—it could potentially protect pricing and margins better.
The Porsche/MHP deal therefore fits the broader strategic shift.
9. But There Is a Major Risk: MHP’s Revenue Decline
This is the biggest negative argument.
MHP’s revenue fell from:
€830 million → €742 million
between 2024 and 2025.
So investors should not simply assume that €742 million of revenue will automatically become additional high-margin TCS revenue.
There are several questions:
- Can TCS stop the revenue decline?
- Can it improve MHP’s margins?
- Can it shift some work to offshore delivery?
- Can it retain MHP’s consulting talent?
- Can it expand MHP beyond Porsche?
- How quickly will the acquisition become earnings-accretive?
These questions will matter more than the headline acquisition price.
10. Brokerages Are Divided on TCS Stock
This is where the investment story becomes particularly interesting.
Emkay Global
Rating: ADD
Target: ₹2,600
Emkay sees strategic benefits from the Porsche partnership and MHP acquisition, particularly in automotive consulting, AI and European expansion. Its target is based on 16× June 2028E EPS.
At ₹2,342, ₹2,600 represents roughly:
+11% upside
Deven Choksey Research
Recommendation: Accumulate
Target: ₹2,525
The brokerage also sees strategic value in the MHP acquisition and Porsche partnership, while highlighting margins as an important factor.
From ₹2,342:
₹2,525 = ~7.8% upside
Morgan Stanley
Rating: Equal-weight
Target: ₹2,200
Morgan Stanley views the acquisition as strategically complementary but expects the immediate financial impact to remain limited.
Its estimates suggest roughly 3% revenue growth contribution and less than 1% PAT contribution, assuming mid-single-digit margins.
That means the brokerage sees strategic value—but not an immediate earnings transformation.
Citi
Rating: SELL
Target: ₹1,825
Citi remains significantly more cautious.
Its main concern is the declining revenue profile of MHP and the broader weakness in Indian IT spending.
From ₹2,342, ₹1,825 would imply approximately:
22% downside
Broker View at a Glance
| Brokerage | View | Target |
|---|---|---|
| Emkay | ADD | ₹2,600 |
| Deven Choksey | Accumulate | ₹2,525 |
| CLSA | Hold | ₹2,326 |
| Morgan Stanley | Equal-weight | ₹2,200 |
| JM Financial | ADD | ₹2,205 |
| Citi | SELL | ₹1,825 |
The range itself tells the story.
₹1,825 → ₹2,600
That’s a very wide difference.
It shows that the market is still uncertain about TCS’s future growth trajectory.
11. What About the ₹2,556 Fair Value?
The valuation shown in your screenshot uses:
CMP: ₹2,254.30
Fair Value: ₹2,556
At that screenshot price, the implied upside to fair value was approximately:
13.4%
However, after the August 28 close of ₹2,342, the same ₹2,556 fair-value assumption would imply roughly:
9.1% upside
So the valuation case has improved, but the stock has already recovered from the screenshot’s CMP.
This fair-value figure should be treated as an analytical estimate, not a guaranteed target.
12. TCS Technical Setup
After the strong move on August 28, traders should watch the following zones.
Immediate Support
₹2,280–₹2,300
Strong Support
₹2,200–₹2,250
Immediate Resistance
₹2,350–₹2,400
Major Resistance
₹2,500–₹2,525
Higher Target Zone
₹2,600
A sustained move above ₹2,400 could improve the short-term technical structure.
A failure near ₹2,350–₹2,400 followed by a break below ₹2,280 could bring profit booking back into the stock.
13. Bull Case for TCS
The bullish thesis is straightforward.
Porsche + MHP
↓
European automotive access
↓
AI + manufacturing expertise
↓
Higher-value consulting
↓
More European clients
↓
Potential margin improvement
↓
Long-term growth acceleration
If TCS successfully integrates MHP and converts the Porsche relationship into a broader European automotive franchise, the current valuation could eventually look more attractive.
14. Bear Case for TCS
The bearish thesis is equally clear.
MHP revenue declining
Weak global IT spending
AI disruption
European economic uncertainty
Limited near-term earnings contribution
could mean that the Porsche deal looks strategically impressive but has only a modest impact on earnings.
That’s essentially why some brokerages remain cautious despite the headline deal.
15. The Most Important Number Isn’t €1.25 Billion
This is perhaps the biggest takeaway.
Investors may focus on:
€1.25 billion Porsche deal
But the more important numbers over the next few quarters will be:
MHP revenue growth
MHP EBIT margin
TCS total revenue growth
AI revenue growth
Deal TCV conversion
Operating margin
European client growth
If MHP’s revenue starts growing again and margins improve, the acquisition thesis becomes much stronger.
If revenue continues falling, the market could conclude that TCS bought a strategic asset—but not a growth engine.
16. Final Verdict: Is TCS a Buy?
The Porsche/MHP transaction is strategically positive, but it should not automatically be interpreted as a massive near-term earnings catalyst.
The strongest argument for TCS is the combination of:
AI + Automotive + Europe + Consulting + Manufacturing
The biggest risk remains:
weak IT demand + MHP revenue decline + uncertain earnings impact.
At the latest available close of ₹2,342, the stock is already above several brokerage targets, including Morgan Stanley’s ₹2,200 and JM Financial’s ₹2,205, while remaining below bullish targets such as Emkay’s ₹2,600 and Deven Choksey’s ₹2,525.
Therefore, the stock is now entering a valuation-versus-growth battle.
Bullish above ₹2,400
A sustained breakout above ₹2,400 could strengthen the recovery setup.
Neutral around ₹2,300–₹2,400
This remains the consolidation and profit-booking zone.
Bearish below ₹2,280
A decisive breakdown could reopen the downside.
Long-term bullish trigger
The real confirmation would come from MHP revenue stabilisation + margin improvement + sustained AI-led deal growth.
Conclusion
TCS’s Porsche deal is much more than a simple acquisition.
The €320 million MHP purchase gives TCS a German automotive consulting platform, while the €1.25 billion five-year Porsche partnership gives it a long-term opportunity to participate in AI-led transformation across engineering, manufacturing and mobility.
But investors should not confuse strategic importance with immediate earnings impact.
The market will ultimately judge this deal through numbers.
If TCS can turn MHP’s declining revenue profile around, improve margins and use Porsche as a gateway to more European automotive clients, the acquisition could become a significant long-term growth catalyst.
If not, the Porsche headline may remain strategically impressive without materially changing TCS’s near-term earnings trajectory.
For TCS shareholders, the next big story is no longer the announcement.
It is the execution.
Disclaimer
This article is for educational and informational purposes only and should not be considered investment or financial advice. The share-price levels, valuation estimates, analyst targets and scenarios mentioned above are subject to change. Past performance does not guarantee future returns. Investors should conduct their own research and consult a SEBI-registered investment adviser before making investment decisions. Trading and investing in equities involve market risk and possible loss of capital.
10 SEO titles :
- TCS Porsche Deal: Why the ₹13,958 Crore AI Partnership Matters for TCS Stock
- TCS Share Price: Porsche’s €1.25 Billion Deal Could Change the Growth Story
- TCS Buys Porsche’s MHP: What Investors Need to Know About the ₹3,575 Crore Deal
- TCS Porsche Deal Explained: AI, MHP Acquisition and the Road Ahead for TCS Stock
- TCS Stock Analysis: Porsche Deal, MHP Acquisition and Future Growth Potential
- TCS Buys MHP for €320 Million: Is This the Big AI Growth Trigger?
- TCS–Porsche ₹13,958 Crore Deal: 5 Things Every Investor Should Know
- TCS Share Price Outlook: Will the Porsche AI Deal Trigger a Re-Rating?
- TCS Porsche Partnership: The Hidden Strategy Behind the MHP Acquisition
- TCS Stock: Porsche AI Deal, MHP Acquisition and What Comes Next