
The Bank of Japan, Yen and the Next Global Liquidity Shock
For years, global investors have been trained to watch Washington.
Every Federal Reserve meeting, every inflation print and every statement from the U.S. Treasury can move markets within minutes.
But in September 2026, another central bank has moved to the centre of the global macro trade:
The Bank of Japan (BoJ).
The reason is simple.
Japan sits at the intersection of currency markets, global bond markets, carry trades and international liquidity. A stronger Yen and higher Japanese interest rates could force leveraged investors to reconsider positions that have benefited from years of relatively cheap Yen funding.
At the same time, the global economy is facing a second shock: oil above $100 per barrel because of the continuing Middle East conflict.
That creates a potentially dangerous combination:
Higher Japanese rates + stronger Yen + carry-trade unwinding + $100+ oil + higher global inflation.
And for Indian investors, the consequences could be particularly important.
1. The Invisible Thread Connecting Tokyo to Wall Street and Mumbai
The global financial system is not a collection of independent markets.
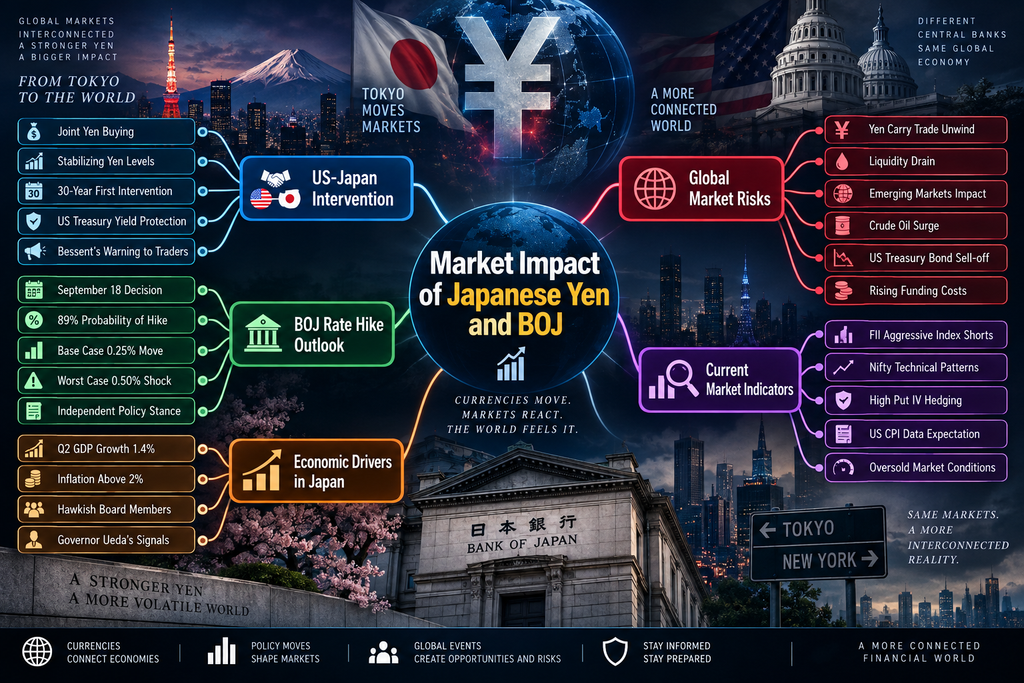
A policy decision in Tokyo can influence:
USD/JPY → global bond yields → carry trades → equity positioning → emerging-market currencies → Nifty
This is why the September BoJ meeting matters far beyond Japan.
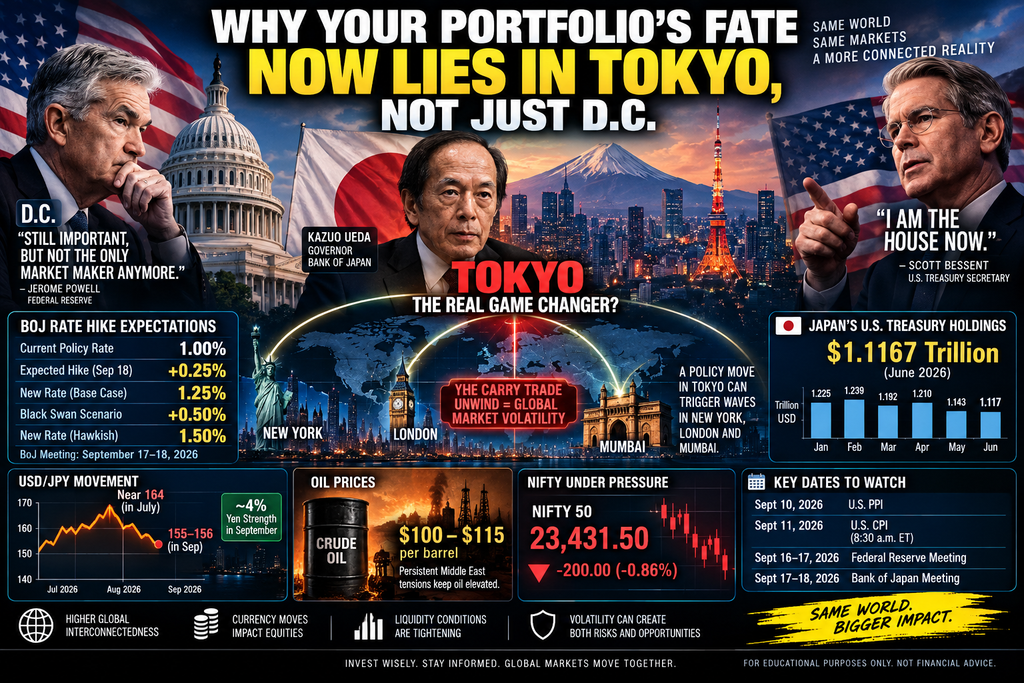
The Bank of Japan currently guides its overnight rate at around 1.0%, after raising rates to that level in June. Its next monetary policy meeting is scheduled for September 17–18.
Markets are now heavily focused on whether the BoJ will raise the rate another 25 basis points to 1.25%.
A Reuters poll published September 9 found that the BoJ is widely expected to move to 1.25% on September 18, with economists also expecting the policy rate to eventually reach around 1.75% by Q2 2027.
That is a major change from the ultra-loose monetary environment that helped support the global carry trade.
2. Scott Bessent’s “House” Warning Is More Important Than It Looks
U.S. Treasury Secretary Scott Bessent has openly highlighted Washington’s strategic advantage in the currency market, particularly after the coordinated U.S.-Japan yen-buying intervention.
Reuters reported that Bessent warned investors against betting against the intervention because he had access to information about the policy process.
The message to currency traders is effectively:
Do not assume Tokyo and Washington will simply stand by while the Yen collapses.
This matters because Japan has already demonstrated that it is willing to intervene aggressively.
In August, Japan’s foreign reserves fell by $79.6 billion, or 6.18%, to $1.208 trillion, following a record currency intervention. Japan reportedly spent about ¥15.4 trillion ($98.7 billion) on yen-buying operations between July 30 and August 26.
The intervention helped move USD/JPY away from its extreme levels near 164.
By early September, the Yen was trading around the 155–156 area, while the currency had gained roughly 4% during September as expectations of BoJ tightening increased.
That is a dramatic reversal.
3. The $1.1 Trillion Treasury Connection
One reason Washington cares so much about Japanese financial stability is Japan’s enormous exposure to U.S. government debt.
The latest U.S. Treasury TIC data show Japan held approximately:
$1.1167 trillion of U.S. Treasuries in June 2026.
That makes Japan one of the largest foreign holders of U.S. government securities.
The number has also moved significantly during the year.
| Month | Japan’s U.S. Treasury holdings |
|---|---|
| January 2026 | $1.225T |
| February | $1.239T |
| March | $1.192T |
| April | $1.210T |
| May | $1.143T |
| June | $1.117T |
This is where the story becomes interesting.
Japan’s currency intervention can involve selling dollar assets and buying Yen. That does not mean every dollar of intervention mechanically translates into Treasury selling, but large-scale intervention can interact with Japan’s reserve composition and U.S. bond markets.
In fact, Reuters reported that Japan’s August intervention involved selling foreign securities, primarily U.S. Treasuries, while Japan also had access to a Federal Reserve liquidity facility designed to reduce pressure on Treasury liquidation.
So the real concern for Washington is not simply:
“Is the Yen weak?”
It is:
“Could Yen instability become a U.S. Treasury-market problem?”
4. The 0.25% BoJ Threshold: Baseline or Trap?
This is where the market mathematics becomes important.
The current BoJ policy rate is approximately:
1.00%
A standard 25-basis-point hike would take it to:
1.25%
That is now the market’s central expectation.
Reuters’ latest poll showed strong expectations for a September move to 1.25%, while more than 80% of analysts surveyed believed the recent U.S.-Japan intervention had reduced political resistance to a rate hike.
But there is a second scenario.
What if the BoJ goes to 1.50%?
That would represent a 50-basis-point hike from the current 1.00% rate.
Such a move would be substantially more aggressive than the market’s expected 25-bps step.
It would send a powerful message:
The BoJ is no longer simply normalizing policy—it is willing to accelerate tightening.
That could produce a much larger reaction in:
- USD/JPY
- Japanese government bonds
- global bond yields
- carry trades
- high-beta equities
- emerging-market currencies
- leveraged positions
However, investors should not automatically assume a 50-bps hike is likely. Current polling points much more strongly toward 1.25%.
5. Japan’s Economy Is Giving the BoJ Room to Tighten
The biggest difference between 2026 and Japan’s previous deflationary decades is that the economy is showing more resilience.
Japan’s Q2 2026 GDP was revised to an annualized 1.4% growth rate, up from the preliminary 1.1% estimate. Quarterly growth was 0.4%.
Real wages also rose 2.4% year-on-year in July, marking seven consecutive months of growth.
That matters because the BoJ needs evidence that the economy can withstand higher interest rates.
The inflation picture is also becoming more important.
Japan’s July core CPI accelerated to 1.8% year-on-year, while the measure excluding fresh food and fuel reached 1.9%. Wholesale inflation was considerably hotter at 7.2%.
Tokyo’s core inflation had also reached 1.9% in July, while the measure excluding fresh food and fuel reached 2.0%.
And on September 10, BoJ board member Kazuyuki Masu warned that the central bank may need to raise rates rapidly if inflation accelerates, arguing that real interest rates remain too low.
That is precisely the kind of communication markets interpret as hawkish.
6. The Great Yen Carry Trade Unwind
This is the part that matters most for global investors.
For years, investors could borrow Yen at relatively low interest rates and deploy that money into higher-return assets elsewhere.
The strategy is commonly known as the:
Yen Carry Trade
The basic mechanism is:
Borrow Yen → Convert to dollars/other currencies → Buy higher-yielding assets → Earn the interest-rate differential.
The strategy works particularly well when:
- Yen remains weak
- Japanese rates stay low
- global volatility remains subdued
- asset prices rise
But the trade can work in reverse.
If the Yen suddenly strengthens:
Yen rises → foreign assets fall in Yen terms → borrowing cost rises → leveraged positions become less attractive → investors sell assets → Yen strengthens further
That creates a feedback loop.
The danger is not simply a BoJ hike.
The real danger is:
BoJ tightening + Yen appreciation + forced deleveraging.
That is why a relatively small Japanese rate increase can potentially have a disproportionately large impact on global markets.
7. The Twin Macro Shock: Yen Tightening + $100 Oil
This is where the September 2026 setup becomes unusual.
Normally, investors might handle one major macro shock.
But markets are currently dealing with two.
Shock No. 1 — Global liquidity tightening
BoJ:
1.00% → potentially 1.25%
Stronger Yen:
Carry trade becomes less attractive
Potential consequence:
Global deleveraging
Shock No. 2 — Energy inflation
Brent:
Above $100/barrel
Reuters reported that Brent moved above $100 as Middle East tensions intensified, while the oil shock has also contributed to higher inflation expectations and rising bond yields.
The combination becomes:
Liquidity contraction + inflation acceleration
That is a difficult environment for expensive growth assets.
8. Why India Is Particularly Vulnerable
India imports a large portion of its crude oil requirements.
Therefore:
Higher crude → larger import bill → pressure on rupee → imported inflation
And we are already seeing the currency respond.
On September 10, the Indian rupee fell for a third consecutive session to around:
₹95.44 per U.S. dollar
Reuters attributed the pressure partly to the oil rally and increased dollar demand. Oil had risen more than 6% during the week.
The RBI has already been responding.
Reuters reported that the RBI conducted additional dollar-rupee sell/buy swaps, including around $600–700 million on September 10, after a roughly $1 billion operation the previous day, in an effort to manage rupee liquidity and currency pressures.
This is an important signal.
India is not only dealing with:
FII selling
It is also dealing with:
Oil + currency + global rates + liquidity.
9. What Happens to Nifty If the Carry Trade Unwinds?
The Nifty does not need a domestic recession to fall.
Global portfolio flows can become the transmission mechanism.
Imagine this sequence:
Stage 1
BoJ raises rates to 1.25%.
Stage 2
Yen strengthens sharply.
Stage 3
Global investors reduce Yen-funded leverage.
Stage 4
High-beta assets are sold.
Stage 5
Emerging-market currencies weaken.
Stage 6
FII hedging increases.
Stage 7
Indian equities face additional selling pressure.
This is why the Nifty can decline even when India’s domestic economic fundamentals remain relatively healthy.
10. But There Is a Crucial FII Detail
One should not automatically interpret heavy FII futures shorts as proof that foreign investors have abandoned India.
The derivatives market and cash market can tell different stories.
A trader may:
- Remain invested in cash equities
- Buy protective puts
- Short index futures
- Reduce beta
- Hedge currency exposure
That means high FII short positions can sometimes represent insurance rather than an outright bearish conviction.
This distinction is extremely important.
If the market is already heavily hedged and a major negative event fails to materialize, those shorts can become fuel for a powerful short-covering rally.
11. The September 11 CPI Is the First Major Test
The BoJ is not the only event investors should watch.
The U.S. August CPI is scheduled for:
September 11, 2026
The official U.S. Bureau of Labor Statistics calendar confirms the release for 8:30 a.m. ET.
Current market expectations cited by Reuters are approximately:
| U.S. August CPI | Market expectation |
|---|---|
| Headline monthly | +0.4% |
| Core monthly | +0.2% |
| Headline YoY | 3.4% |
| Core YoY | 2.4% |
This creates another potential volatility event.
Hot CPI + hawkish BoJ
This would be the worst combination for global risk assets.
Why?
Because investors could simultaneously price:
Higher U.S. rates + higher Japanese rates + stronger Yen + higher oil
That would represent a significant tightening of global financial conditions.
12. The September 17–18 “Global Liquidity Test”
The calendar is now extremely important.
September 10
U.S. PPI
September 11
U.S. CPI
September 16–17
Federal Reserve policy meeting
September 17–18
Bank of Japan policy meeting
The U.S. PPI was scheduled for September 10 and the CPI for September 11, according to the official BLS calendar.
The BoJ’s official schedule confirms its policy meeting for September 17–18.
That means markets are entering one of the most important macro windows of the month.
13. Three Scenarios for September 18
🟢 Scenario 1: BoJ 1.25% + Dovish Guidance
This is arguably the most manageable scenario.
The BoJ hikes 25 bps but signals that future increases will be gradual.
Possible reaction:
- Yen strengthens moderately
- Carry trade remains relatively orderly
- Global equities stabilize
- Nifty gets short-covering support
- Bond yields remain manageable
This could produce a relief rally.
🟡 Scenario 2: BoJ 1.25% + Very Hawkish Guidance
This could be more dangerous than the actual rate hike.
The BoJ could deliver the expected 25 bps but signal:
“More hikes are coming quickly.”
Markets could immediately start pricing 1.50% and beyond.
Potential result:
Yen ↑
Carry trade ↓
Global volatility ↑
Nifty pressure ↑
This is the scenario many traders may underestimate.
🔴 Scenario 3: BoJ 1.50% Surprise
This would be the genuine “Black Day” scenario described in the original article.
It would represent a 50-bps hike from the current 1.00% policy rate.
The market reaction could be much larger because the surprise itself would matter more than the absolute rate.
Possible chain reaction:
BoJ 1.50% → Yen spikes → carry positions unwind → global equities sell → EM currencies weaken → Nifty volatility explodes
But again:
This is a risk scenario, not the current consensus.
The current Reuters poll strongly favours 1.25%, not 1.50%.
14. The Four Numbers Investors Should Watch
Forget the noise.
For the next few sessions, these four numbers matter enormously.
1. USD/JPY
This is arguably the most important global-market signal.
A sharp Yen appreciation could indicate accelerating carry-trade unwinding.
The dollar was recently trading near a seven-month low against the Yen as expectations for BoJ tightening increased.
2. Brent crude
$100 is now the psychological battlefield.
A sustained move toward:
$105 → $110 → $120
would materially increase inflation concerns.
3. U.S. 10-year Treasury yield
If oil rises while Treasury yields also rise, the combination becomes significantly more dangerous for equity valuations.
Reuters noted that U.S. 10-year yields have recently reached their highest levels since 2023.
4. Nifty
Watch whether the index can absorb global macro pressure without breaking major technical supports.
A sharp decline accompanied by rising volatility and aggressive FII futures shorts could eventually create the conditions for short covering.
15. The Real Question: Is Tokyo Really the New Market Maker?
Not exactly.
The Federal Reserve remains extremely important.
But the market has entered an environment where BoJ policy can amplify moves created elsewhere.
Think of it this way:
Washington controls one side of global liquidity.
Tokyo controls another critical funding channel.
And when those two policy directions move simultaneously, the impact can become much larger.
That is why investors should stop viewing the BoJ as merely a Japanese domestic institution.
The Yen is a global funding currency.
And when the cost of that funding changes, global portfolios can react.
Conclusion: September 18 Is Not Just a BoJ Meeting
The biggest mistake investors can make is to look at the September 18 decision in isolation.
The real event is the combination of:
**U.S. inflation
- Federal Reserve policy
- BoJ tightening
- Yen appreciation
- Carry-trade positioning
+ $100+ oil - Emerging-market currency pressure**
That is the real macro equation.
Japan’s economy has become strong enough for the BoJ to contemplate another rate increase. Q2 GDP was revised to 1.4% annualized, real wages are rising, inflation pressures remain significant, and BoJ officials are increasingly warning that policy may need to tighten further.
At the same time, Japan has already demonstrated its willingness to intervene heavily in currency markets, spending roughly $98.7 billion during its latest intervention period.
And the Yen is already responding.
The question is no longer simply:
“Will the BoJ hike?”
The more important question is:
“What happens to global leverage if the Yen suddenly becomes significantly more expensive to borrow?”
That is why Tokyo matters.
And if the BoJ surprises markets with a substantially more aggressive path while oil remains above $100, the September 2026 market could become a genuine test of global liquidity.
For Indian investors, the key transmission channels are clear:
USD/JPY → global liquidity → FII positioning → USD/INR → crude oil → Nifty
The market does not need all six to move at once.
If even three or four move aggressively in the same direction, volatility can become extreme.
September 17–18 may therefore determine much more than the next Japanese interest rate. It could reveal whether the global carry trade still has enough room to survive.
Disclaimer
This article is for educational and informational purposes only and does not constitute financial, investment, trading, legal, tax, or professional advice. Market forecasts, interest-rate scenarios, currency levels, crude-oil projections, technical levels, and geopolitical assessments are subject to change and are not guaranteed. Readers should conduct their own research and consider their financial objectives and risk tolerance before making any investment or trading decision. Past performance does not guarantee future results. Please consult a SEBI-registered investment adviser or other qualified financial professional where appropriate. The author/publisher accepts no responsibility for any loss arising from reliance on the information presented in this article.
SEO Titles
- BoJ Rate Hike 2026: Why Japan Could Trigger the Next Global Market Shock
- Bank of Japan September 2026: Will the Yen Carry Trade Collapse?
- BoJ 1.25% Rate Hike: What It Means for Nifty, FII Flows and Global Markets
- Yen Carry Trade Unwind: Why Indian Stocks Could Be the Next Casualty
- Japan Rate Hike September 18: The Global Liquidity Risk Investors Must Watch
- USD/JPY, BoJ and Nifty: Why Tokyo Matters More Than Washington Right Now
- BoJ Rate Hike 2026 Explained: The $1.1 Trillion Treasury and Carry Trade Risk
- Japan Yen Crisis: Could a BoJ Rate Hike Trigger a Global Stock Market Sell-Off?
- September 18 BoJ Meeting: 1.25% Hike or a 1.50% Black Swan Shock?
- Why the Yen Could Decide the Fate of Nifty and Global Markets